Payroll Services in Canada

Fully managed Canadian payroll across all thirteen jurisdictions

CPP, CPP2 and EI remitted on the schedule the CRA has assigned you, Quebec run properly on QPP, QPIP and the Health Services Fund, employer health tax and workers’ compensation handled province by province, and T4s and RL-1s filed on time, with a named specialist a phone call away.

Run through your own Canadian entity, or through ours, with your global view consolidated in Portico.

Rated 5/5 by Gartner users

Talk to an expert

Book a call to discuss your Canada payroll needs.

Calculate Your Employee Costs in Canada

Enter a gross salary to see the full annual cost of a Canadian employee – CPP or QPP, Employment Insurance and employer payroll tax included in your total spend per employee. Every contribution is capped, so the effective rate falls as salary rises.

Employment Cost Calculator
Canada
British Pound
  • British Pound
  • Euro
  • US Dollar
  • Indian Rupee
CAD
*Indicative figures only and not definitive legal advice. Local regulations change frequently. Consult an expert
Canada
British Pound Canada
Base Salary (per month)
Employer Contributions
Total Cost (Annual)
Total Cost (Monthly)
Employer of Record services in Learn more Payroll Outsourcing in Learn more

Know your Canadian employment costs before you commit

Tell us the role, the salary and the province – we’ll send back the full Canadian employer cost, employer health tax and workers’ compensation included, within one business day.

Get a Custom Payroll Quote

Employer Costs in Canada Explained

Statutory employer costs in Canada are roughly 9% to 11% of salary in most provinces, and about 14% in Quebec. The federal layer is CPP at 5.95% matched by the employer on earnings to $74,600, CPP2 at 4% on the slice to $85,000, and Employment Insurance at 2.282% on earnings to $68,900 – a combined maximum of $6,218.75 per employee. The provincial layer is an employer payroll tax in five jurisdictions only, at 0% to 4.26%, plus mandatory workers’ compensation from $0.95 to $2.65 per $100 of payroll. Because every contribution is capped, the effective rate falls as salary rises: an $80,000 employee costs an Ontario employer about $8,563 in statutory contributions, while a $150,000 employee costs about $10,641 – 10.7% against 7.1%. And one rate is about to fall: CPP drops from 5.95% to 5.75% on 1 January 2027, the first cut in the plan’s history. Here’s the breakdown.

For 2026 the Canada Pension Plan rate is 5.95% for the employee and 5.95% matched by the employer, on pensionable earnings between the $3,500 basic exemption and the Year’s Maximum Pensionable Earnings of $74,600 – a maximum of $4,230.45 each. CPP2, the second additional contribution in place since 2024, adds 4% each on the slice of earnings between $74,600 and the Year’s Additional Maximum Pensionable Earnings of $85,000, a maximum of $416 each. An employee earning $74,600 or less pays no CPP2 at all. Employment Insurance runs at 1.63% for the employee and 1.4 times that – 2.282% – for the employer, on insurable earnings to $68,900, giving maximums of $1,123.07 and $1,572.30.

One point that catches multi-employer situations: the $3,500 basic exemption is prorated per pay period but not between employers, so each employer applies it in full and any over-deduction is reconciled on the employee’s personal return. And the CRA specifically recommends its Payroll Deductions Online Calculator over the printed tables where an employee crosses the $74,600 ceiling mid-year, because the tables can over- or under-deduct at that point.

The change worth planning for is a rate cut, which is not something Canadian payroll has seen before. Bill C-30, the Spring Economic Update 2026 Implementation Act, received royal assent on 18 June 2026 and reduces the base CPP contribution rate from 4.95% to 4.75% with effect from 1 January 2027, taking the combined statutory base rate from 9.90% to 9.50%. The additional rates are unchanged, so the total employee and employer rate falls from 5.95% to 5.75%. That is worth up to $142.20 per employee per side at the ceiling. It is stated in the CRA’s own July 2026 payroll formulas, and it is not reflected in any 2026 figure.

Federal income tax for 2026 runs at 14% to $58,523, then 20.5%, 26%, 29% and 33% above $258,482. The bottom rate is a clean 14% for the whole of 2026 – worth stating precisely, because the cut took effect on 1 July 2025 and produced a blended 14.5% for the 2025 year only. The basic personal amount is $16,452, clawed back on a straight line to $14,829 across the fourth bracket.

On top sits a provincial or territorial scale, set independently by each jurisdiction, so the same gross salary produces a different net in Toronto, Calgary and Montreal. Three provinces changed mid-2026, which means two sets of tables apply in one year: British Columbia’s lowest rate rose to 5.60% from 1 July, Prince Edward Island added a 20% bracket above $200,000, and Newfoundland and Labrador raised its basic personal amount. Alberta introduced a new 8% bracket on the first $60,000 for 2026. Withholding is set from each employee’s federal and provincial TD1 forms, and the CRA publishes two editions of the T4127 payroll formulas in a year like this one – the 122nd effective 1 January and the 123rd effective 1 July.

Quebec runs its own income tax entirely, administered by Revenu Québec: 14% to $54,345, then 19%, 24% and 25.75% above $132,245, with a basic personal amount of $18,952. A Quebec employee has federal tax, Quebec tax, QPP, QPP2, EI at the reduced Quebec rate and QPIP all coming off one payslip, reported to two tax authorities on two slips.

Five jurisdictions tax your payroll directly. Ontario’s Employer Health Tax exempts the first $1,000,000 of Ontario remuneration, on a scale rising to 1.95%, with the exemption withdrawn entirely once the employer or associated group reaches $5,000,000 of Ontario payroll; the annual return is due 15 March. British Columbia exempts the first $1,000,000, charges 5.85% on the slice to $1,500,000 and 1.95% of total remuneration above that, with the return due 31 March. Manitoba’s exemption rose to $2,500,000 for 2026, then 4.3% on the excess to $5,000,000 and 2.15% of total payroll above it. Newfoundland and Labrador exempts $2,000,000 and charges 2%. Quebec’s Health Services Fund runs on a sliding scale to 4.26% above $7,800,000 of payroll – a threshold that stopped being indexed in 2026.

Note how the notch rates work, because they are where the surprises are. Above the upper threshold in British Columbia, Manitoba and Quebec the exemption disappears and the rate applies to total payroll, not to the excess. Crossing that threshold by a dollar can cost tens of thousands. Associated groups share one exemption, and part-year employers prorate it.

Alberta, Saskatchewan, Nova Scotia, New Brunswick, Prince Edward Island and Yukon levy no employer payroll tax at all. Northwest Territories and Nunavut charge 2% of remuneration, but the statutory incidence is on the employee – your obligation is to withhold, remit and file an annual return.

Workers’ compensation is separate, mandatory, entirely employer-funded and set by thirteen different boards. Average 2026 rates run from $0.95 per $100 of assessable payroll in Manitoba and $1.23 at Ontario’s WSIB – its lowest in more than fifty years – to $2.65 in Nova Scotia. Each board also sets a maximum assessable earnings ceiling, and these vary enormously: $79,900 in Nova Scotia against $171,500 in Manitoba. The ceiling caps both your premium base and the injured worker’s benefit, so a low rate on a high ceiling is not always cheaper than the reverse.

Quebec is the single biggest source of error in Canadian payroll for employers new to the country, because it is not a provincial variation on a federal system – it is a parallel system. Quebec employees contribute to the Quebec Pension Plan, not CPP: 6.30% employee and 6.30% employer on the same $74,600 ceiling and $3,500 exemption, a maximum of $4,479.30 each – $248.85 more per employee than CPP. QPP2 mirrors CPP2 at 4% to $85,000. The federal EI rate is lower in Quebec, at 1.30% employee and 1.82% employer, precisely because Quebec runs its own parental insurance plan; that plan, QPIP, then charges 0.430% of insurable earnings to the employee and 0.602% to the employer on a much higher ceiling of $103,000.

Then the employer-only items. The Health Services Fund contribution runs from 1.25% for primary and manufacturing employers under $1,000,000 of payroll, or 1.65% for everyone else, up a sliding scale to 4.26% above $7,800,000. A new contribution holiday applies for 2026 and 2027 to employers whose payroll is more than half attributable to agriculture, forestry or fishing. The labour standards contribution is 0.06% of remuneration to a ceiling of $103,000, remitted annually rather than with your periodic source deductions. And any employer with more than $2,000,000 of Quebec payroll must spend at least 1% of it on eligible training, or pay the shortfall into the Workforce Skills Development and Recognition Fund.

Filing is doubled. Quebec employees need an RL-1 slip and an RL-1 Summary to Revenu Québec, on top of the federal T4, both due the last day of February. Remittance frequencies are set separately by Revenu Québec on its own thresholds. And under the Charter of the French Language, offers of employment, employment contracts and documents setting out conditions of work must be in French – with employers of 25 or more employees required to register with the OQLF since 1 June 2025.

The arithmetic result: for the same $80,000 employee, a large employer’s statutory cost is about $8,563 in Ontario and about $11,119 in Quebec. Quebec is roughly 30% more expensive, and that gap is a budgeting fact rather than a rounding difference.

Employment standards are provincial, and the differences are real. Vacation starts at two weeks and 4% of gross earnings in most provinces, rising to three weeks and 6% – but the trigger is three years in Quebec, five in Ontario, British Columbia, Alberta and Manitoba, eight in New Brunswick and fifteen in Newfoundland and Labrador. Saskatchewan starts everyone at three weeks and 5.77%. Statutory holidays run from six in Nova Scotia and Newfoundland to nine in Ontario, Alberta and Manitoba and eleven in British Columbia, and only British Columbia, Manitoba, PEI, Yukon and the Northwest Territories treat 30 September as a paid statutory holiday. Paid sick leave exists in only three provinces – five days in British Columbia, two in Quebec, up to three by tenure in PEI – with every other province offering unpaid job-protected leave only.

Termination is where the exposure sits. Statutory notice is one to eight weeks in most provinces, capped at four in New Brunswick and six in Newfoundland and Labrador. Ontario is the only province with statutory severance in addition to notice: an employee with five or more years of service, where the employer’s global payroll is at least $2,500,000 or fifty or more employees were severed within six months on a closure, receives one week’s pay per year of service, prorated for part years, capped at 26 weeks. Critically, statutory notice is a floor everywhere – common-law reasonable notice, and in Quebec the délai de congé under the Civil Code, is typically far longer where the contract does not validly limit it. A payroll provisioning only the statutory minimum will under-provision every termination.

A Record of Employment is required on every interruption of earnings – seven consecutive days without work and insurable earnings, or a drop below 60% of normal weekly earnings through illness or leave – and it is required whether or not the employee intends to claim EI. Electronic ROEs are due five calendar days after the end of the pay period; paper ROEs within five calendar days of the interruption. Paper ROEs remain valid: Service Canada encourages ROE Web but has not mandated it, which is worth knowing because a good deal of published guidance says otherwise.
Two live pay transparency regimes. Since 1 January 2026, Ontario employers with 25 or more employees must state expected compensation or a range in every publicly advertised job posting, with the range spanning no more than $50,000 a year and no requirement above $200,000; must disclose any use of AI in screening; must not require Canadian experience; must say whether the posting is for an existing vacancy; and must tell every interviewed applicant the outcome within 45 days. British Columbia has required pay ranges in postings since November 2023, and its reporting obligation reaches employers with 50 or more BC employees on 1 November 2026.

Canadian statutory payroll rates, 2026

Contribution Employer Employee Applies to
CPP – base and first additional 5.95% 5.95% $74,600 YMPE, less the $3,500 basic exemption. Maximum $4,230.45 each. Falls to 5.75% on 1 January 2027
CPP2 – second additional 4.00% 4.00% Earnings from $74,600 to $85,000 (YAMPE) only. No basic exemption. Maximum $416 each
Employment Insurance – outside Quebec 2.282% (1.4 × employee) 1.63% $68,900 maximum insurable earnings. Maximum $1,572.30 employer, $1,123.07 employee
Employment Insurance – Quebec 1.820% 1.30% Lower because QPIP covers parental benefits. Maximum $1,253.98 employer, $895.70 employee
QPP – Quebec, base and first additional 6.30% 6.30% Replaces CPP for Quebec employees. Same $74,600 ceiling and $3,500 exemption. Maximum $4,479.30 each
QPP2 – Quebec 4.00% 4.00% Earnings from $74,600 to $85,000. Maximum $416 each
QPIP – Quebec parental insurance 0.602% 0.430% $103,000 maximum insurable earnings. Maximum $620.06 employer, $442.90 employee
Quebec labour standards contribution 0.06% Ceiling $103,000 per employee. Remitted annually with the RL-1 Summary, not with source deductions
Federal income tax 14% / 20.5% / 26% / 29% / 33% Withheld from the employee. Bands at $58,523, $117,045, $181,440, $258,482. Basic personal amount $16,452 falling to $14,829
Provincial income tax Varies by jurisdiction Thirteen separate scales. Quebec administers its own: 14% / 19% / 24% / 25.75%, basic personal amount $18,952
Employer payroll tax 0% – 4.26% Levied by Ontario, BC, Manitoba, Newfoundland and Labrador and Quebec only. See the table below
Workers’ compensation $0.95 – $2.65 per $100 Mandatory, employer-funded, thirteen boards. Assessed on payroll up to a per-worker ceiling that varies from $79,900 to $171,500

Employer payroll tax, workers’ compensation and minimum wage by province, 2026

Jurisdiction Employer payroll tax Workers’ comp average, per $100 Max assessable earnings General minimum wage
Ontario $1m exemption, scale to 1.95%; no exemption at $5m+ payroll WSIB – $1.23 $121,700 $17.60 → $17.95 on 1 Oct 2026
Quebec Health Services Fund 1.25%–1.65% rising to 4.26% above $7.8m CNESST – $1.54 $103,000 $16.60 since 1 May 2026
British Columbia $1m exemption; 5.85% notch to $1.5m; 1.95% of total above WorkSafeBC – $1.55 $127,500 $18.25 since 1 Jun 2026
Alberta None WCB-Alberta – $1.46 $110,900 $15.00 – unchanged since 2018, lowest in Canada
Manitoba $2.5m exemption; 4.3% notch to $5m; 2.15% of total above WCB Manitoba – $0.95 $171,500 $16.00 → $16.40 on 1 Oct 2026
Saskatchewan None WCB Saskatchewan – $1.22 $108,223 $15.35 → $15.70 on 1 Oct 2026
Nova Scotia None WCB Nova Scotia – $2.65 $79,900 $16.75 → $17.00 on 1 Oct 2026
New Brunswick None WorkSafeNB – $1.10 $85,800 $15.90 since 1 Apr 2026
Newfoundland & Labrador HAPSET – $2m exemption, then 2% WorkplaceNL – $1.73 $80,935 $16.35 since 1 Apr 2026
Prince Edward Island None WCB PEI – $1.25 $89,300 $17.00 since 1 Apr 2026
Yukon None YWCHSB – $2.20 $107,599 $18.51 since 1 Apr 2026
Northwest Territories 2% – but levied on the employee, withheld by the employer WSCC – $2.40 $116,000 $16.95 → $17.20 on 1 Sep 2026
Nunavut 2% – levied on the employee, withheld by the employer WSCC – $2.40 $117,300 $19.75 → $20.17 on 1 Sep 2026, highest in Canada

How employer cost falls as salary rises: Ontario worked through

Salary CPP CPP2 EI Ontario EHT WSIB Total Effective rate
$60,000 $3,362 $1,369 $1,170 $738 $6,639 11.1%
$80,000 $4,230 $216 $1,572 $1,560 $984 $8,563 10.7%
$100,000 $4,230 $416 $1,572 $1,950 $1,230 $9,399 9.4%
$150,000 $4,230 $416 $1,572 $2,925 $1,497 $10,641 7.1%

The Ontario worked example assumes a large employer above the $5m payroll threshold, so the EHT exemption is unavailable and 1.95% applies to total remuneration, with workers’ compensation at the WSIB 2026 average of $1.23 per $100 to the $121,700 ceiling. Workers’ compensation rates elsewhere are scheme averages; your own rate is set by industry classification and claims experience, and the maximum assessable earnings ceiling caps both your premium base and an injured worker’s benefit. Cross-province rate comparisons are indicative only, because each board weights payroll and industry mix differently. Employer payroll tax exemptions are shared across associated groups and prorated for part-year employers.

Rates, ceilings and thresholds shown are for the 2026 calendar year and were verified on 28 August 2026. Federal figures reset on 1 January; provincial income tax, minimum wages and workers’ compensation rates change on their own schedules, and three provinces changed income tax mid-2026. This page is general information, not tax or legal advice.
How our Canadian payroll service works

1. Map your setup
We confirm your Business Number and RP payroll account, which provinces you employ in and therefore which employment standards, employer payroll tax and workers’ compensation board apply to each employee, your CRA remitter type and the average monthly withholding amount that produced it, whether you have Quebec employees and so need Revenu Québec registration, and whether non-resident employer certification is available to you. Province of employment is the first question, not a detail – it decides vacation, holidays, notice, severance and two separate tax bills.

2. Migrate or onboard

Employees are set up with federal and provincial TD1 forms, the right province of employment for withholding, workers’ compensation classification, and year-to-date CPP, CPP2, EI, QPP and QPIP balances carried over accurately – because each has its own ceiling and a wrong opening balance means a wrong ceiling all year. We register you with each workers’ compensation board and each provincial payroll tax authority you need, and carry over vacation and banked-time balances on the correct provincial basis.

3. Run and review

Each period you receive a payroll report for approval before anything is paid – gross to net per employee, statutory deductions itemised, employer costs by province shown separately, employees approaching a CPP, CPP2, EI or QPIP ceiling flagged, and variances explained. Nothing is paid, filed or remitted until you approve it.

4. File, pay and remit

Salaries are paid in Canadian dollars. Source deductions are remitted on your assigned CRA schedule – quarterly, monthly, or twice or four times a month for accelerated remitters, where the deadline is three working days after each period end. Quebec source deductions and employer contributions go to Revenu Québec on its own schedule. Records of Employment are issued within five days of each interruption of earnings. Employer health tax instalments and annual returns, workers’ compensation declarations, T4s and T4 Summaries by the last day of February, and RL-1s alongside them.

5. Stay current

Canadian payroll changes on 1 January for the federal and most provincial figures, but a good deal moves off-cycle: three provinces changed their income tax mid-2026, four minimum wages rise on 1 October 2026, and the CPP base rate falls on 1 January 2027 – the first cut in the plan’s history. Every year we apply the new ceilings and rates, reload provincial tables when a mid-year edition is published, re-verify the figures on this page, and brief you on what moves your costs. We run the neighbouring markets the same way – see payroll services in the United States and payroll services in the United Kingdom.

Why TopSource for Canadian Payroll

TopSource for payroll, Employer of Record or any other of our services represents a simpler, more reliable and transparent option.

We don’t hide fees or sneak price increases. We run Canadian payroll in-house, not brokered to a local bureau – the same team that files your T4s and RL-1s answers your calls, in English and French. You get a named account manager, one consolidated monthly invoice covering salaries, remittances and fees, and one live Portico view of Canada beside every other country we run for you. Portico syncs with your time-tracking, leave and HR systems via API – set up by our onboarding team, not left to yours. GDPR, SOC 2 and ISO 27001 certified.

Toronto skyline and CN Tower at dusk over Lake Ontario, Canada

Other services
Accelerating your growth in Canada and beyond

TopSource goes far beyond payroll, acting as your end-to-end partner in global workforce management. From Employer of Record (EOR) services and seamless entity setup to localized accountancy and fractional HR support, we cover every aspect of international employment.

Talent gap analysis for businesses

With our Global EOR services, you can hire talent in any country without establishing a legal entity. We handle employment contracts, payroll, benefits, and compliance on your behalf, enabling fast, risk-free global expansion.

On demand access to our fractional and regional HR professionals who understand local laws, cultures, and best practices. Bespoke talent intelligence including salary, business and talent market benchmarking.

Our global entity management team helps you establish and maintain your corporate entities worldwide. We ensure full compliance with local laws and regulations, streamline administrative processes, and minimize risk — so you can focus on growing your business.

We offer comprehensive accounting solutions tailored to meet your international needs. From bookkeeping and financial reporting to tax filings and audits, our services help you maintain transparency, accuracy, and compliance in every jurisdiction.

Meet our experts for Canada

Whether you’re entering the market or scaling operations, our specialists provide the insight and guidance you need to succeed in one of the world’s most dynamic and regulated employment landscapes. With TopSource, you’re backed by real experts, every step of the way.

Meet Our People

Beyond a payroll service
A globalization accelerator

A payroll platform for your employees is just the beginning. We are constantly evaluating your entire organisation to identify compliance issues and ways to accelerate your global growth.
Payroll platform
Global payroll simplified

Your intuitive hub for paying global teams. Simple, powerful, and designed to scale with you — no complexity, just clarity.

Audit
Eliminate barriers to growth

Avoid compliance issues across your global workforce and uncover opportunities to improve profitability. On a quarterly basis we’ll help you audit your global talent strategy to ensure it aligns with your business goals.

Intelligence
Build a data-driven talent strategy

Grow confidently and profitably with access to the latest TopSource insights & data on hiring markets, salary benchmarking & benefits.

Advisory
Expert guidance that turns complexity into clarity.

Whether you’re managing a global acquisition or entering a new market, you get clear guidance to navigate complex decisions, avoid delays, and accelerate your global expansion.

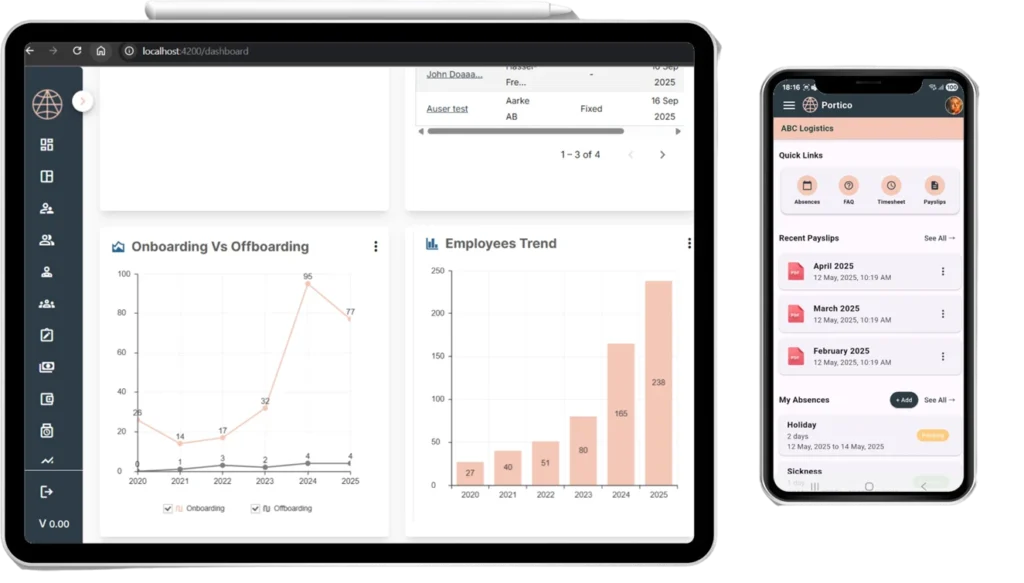
HR and payroll analytics dashboard on tablet and mobile, showing employee trends Map talent availability operate freely in any market

Canadian payroll FAQs

Statutory employer costs in Canada are roughly 9% to 11% of salary in most provinces and about 14% in Quebec, for a large employer above the payroll tax thresholds. On an $80,000 salary in 2026 that is about $8,563 in Ontario, $7,187 in Alberta and $11,119 in Quebec. The percentage falls as salary rises because every contribution is capped: the same Ontario employee costs about 11% of salary at $60,000 and about 7% at $150,000. Add employment standards costs – vacation pay, statutory holidays and any provincial paid sick leave – on top.

The Canada Pension Plan rate for 2026 is 5.95% for the employee and 5.95% for the employer, on pensionable earnings between the $3,500 basic exemption and the Year’s Maximum Pensionable Earnings of $74,600. The maximum contribution is $4,230.45 each. Quebec employees contribute to the Quebec Pension Plan instead, at 6.30% each to a maximum of $4,479.30.

CPP2 is the second additional Canada Pension Plan contribution, in place since 1 January 2024, charged at 4% on the employee and 4% on the employer. It applies only to the slice of pensionable earnings above the Year’s Maximum Pensionable Earnings and up to the Year’s Additional Maximum Pensionable Earnings – for 2026, earnings between $74,600 and $85,000, a maximum of $416 each. No basic exemption applies to CPP2, and an employee earning $74,600 or less pays none.

Yes. The base Canada Pension Plan contribution rate falls from 4.95% to 4.75% on 1 January 2027, taking the combined statutory base rate from 9.90% to 9.50%. Because the additional rates are unchanged, the total employee and employer rate falls from 5.95% to 5.75% – worth up to $142.20 per employee per side at the ceiling. It was legislated by Bill C-30, the Spring Economic Update 2026 Implementation Act, which received royal assent on 18 June 2026, and is stated in the CRA’s July 2026 payroll deductions formulas. It is the first reduction in the plan’s history.

The 2026 Employment Insurance employee premium rate is 1.63% of insurable earnings outside Quebec, and the employer pays 1.4 times that, at 2.282%. Maximum insurable earnings are $68,900, giving maximum annual premiums of $1,123.07 for the employee and $1,572.30 for the employer. In Quebec the rates are lower – 1.30% and 1.82% – because the Quebec Parental Insurance Plan covers maternity and parental benefits instead of federal EI.

Five jurisdictions levy a tax on the employer’s payroll: Ontario and British Columbia through their Employer Health Tax, Manitoba through the Health and Post-Secondary Education Tax Levy, Newfoundland and Labrador through HAPSET, and Quebec through the Health Services Fund. Alberta, Saskatchewan, Nova Scotia, New Brunswick, Prince Edward Island and Yukon levy none. Northwest Territories and Nunavut charge 2% of remuneration, but the tax falls on the employee and the employer withholds it.

Quebec operates a parallel system rather than a provincial variation. Quebec employees contribute to the Quebec Pension Plan at 6.30% rather than CPP at 5.95%, pay a reduced federal EI rate because Quebec runs its own parental insurance plan, and pay QPIP premiums on top. Employers additionally pay the Health Services Fund contribution of up to 4.26% of payroll, a 0.06% labour standards contribution, and a 1% training levy where Quebec payroll exceeds $2,000,000. Quebec employees need an RL-1 slip filed with Revenu Québec as well as a federal T4.

T4 slips and the T4 Summary are due to the CRA by the last day of February following the calendar year, and employees must receive their copies by the same date. Quebec RL-1 slips and the RL-1 Summary are due to Revenu Québec on the same deadline. More than five information returns of a type must be filed electronically, and late filing carries penalties from $100 up to $7,500 depending on slip volume.

Since 1 January 2026, Ontario employers with 25 or more employees must include the expected compensation or a range in every publicly advertised job posting, with the range spanning no more than $50,000 a year. No disclosure is required where expected compensation exceeds $200,000. Postings must also disclose any use of artificial intelligence to screen or select applicants, must not require Canadian experience, and must state whether the posting is for an existing vacancy. Every interviewed applicant must be told the outcome within 45 days.

No Canadian legal entity or permanent establishment is required to have Canadian payroll obligations or to register for them. A non-resident business can obtain a Business Number and an RP payroll account, and must do so before its first remittance is due. A qualifying non-resident employer certified by the CRA on Form RC473 can be relieved of income tax withholding for qualifying employees working in Canada under 45 days in a year, though CPP and EI still apply. If you would rather not register at all, an Employer of Record in Canada engages the employee through an existing Canadian entity.

Couldn’t find what you were looking for?

Looking at other markets too?

We help organizations with employ and pay teams in over 180 countries.