Payroll Services in Germany
Fully managed German payroll – each employee costed on their own Krankenkasse’s Zusatzbeitrag rather than the national average, both contribution ceilings configured separately, contributions in cleared funds on the third-to-last banking day before the month has even finished, and ELStAM, DEÜV and the eAU handled so nobody starts on Steuerklasse VI by accident.

TopSource rated 5/5 by our customers
What German payroll actually involves
German payroll is precise rather than difficult, and the precision is where foreign employers come unstuck. There is no single German employer rate: the figure depends on which health insurance fund each employee belongs to, which trade association the employer falls into, whether the employer has more than thirty people, where the work is performed, and where the salary sits relative to two different contribution ceilings. Contributions are due before the month they relate to has ended, so the amount is estimated and trued up the following month. Wage tax runs on a separate calendar. Sick notes arrive electronically and must be pulled rather than received. Holiday does not expire unless the employer has told each employee, individually, that it will. And working time must be recorded because a court said so in 2022, even though no statute yet says how. None of it is hard. All of it is exact, and almost none of it is uniform across a workforce.
Our Partners Globally




Calculate Your Employee Costs in Germany
Enter a gross annual salary to see employer social insurance in Germany for 2026: pension 9.30% and unemployment 1.30% up to EUR 101,400 a year; health 8.75% at the average Zusatzbeitrag and long-term care 1.80% up to EUR 69,750; the 0.15% insolvency levy; and an estimate for accident insurance. The U1 and U2 levies, set by each employee’s Krankenkasse, are not included, and the health figure moves with the employee’s own fund.
Employment Cost Calculator
*Indicative figures only and not definitive legal advice. Local regulations change frequently. Consult an expertGermany
| British Pound | Germany | |
|---|---|---|
| Base Salary (per month) | ||
| Employer Contributions | ||
| Total Cost (Annual) | ||
| Total Cost (Monthly) |
“Their expertise and understanding of the unique hiring, payment, and human resource practices in each country has been nothing short of outstanding. Our Client Success Manager, has done just that … ensured our success. Her availability and willingness to engage on a personal level has made all the difference.”
“Excellent service, especially from our account manager who has gone above and beyond to help us use the platform effectively. Our manager, significantly simplifies my workload. It is like having your own TopSource HR representative on your team.”
“TopSource has been our go-to resource for international hiring. They are responsive, thorough, respectful and knowledgeable. The Client Success team has provided us with the utmost customer service, and the more we use TopSource, the more, it gives us access to more resources and knowledge.”
Employer Costs in Germany Explained
A German employee costs an employer about 25% of gross at the bottom of the salary range and about 7% at EUR 300,000 – because German employer social insurance is capped in absolute terms. The four statutory branches come to 21.15% on the employer side at the 2026 average health supplement, which is the figure most guides quote, and it is incomplete: it leaves out accident insurance through the Berufsgenossenschaft, the U2 maternity levy payable by every employer regardless of size, the 0.15% insolvency levy, and the U1 sick pay levy for employers with thirty or fewer staff. Add them and a realistic office figure is about 25% for a small employer and about 23% above thirty people. Then it falls, in two steps, because health and long-term care are capped at EUR 5,812.50 a month while pension and unemployment are capped at EUR 8,450. An employee on EUR 110,000 and an employee on EUR 400,000 cost the employer exactly the same in social insurance. Here’s the breakdown.
The figure almost every guide quotes is about 21%, and it is the sum of the four branches’ employer halves and nothing else. For 2026 that is 9.30% pension, 1.30% unemployment, 7.30% health at the general rate, 1.45% as half of the average health supplement and 1.80% long-term care – 21.15% in total. It omits real employer-only costs, and it assumes an average that no individual employee is actually on.
The health supplement is where the simplification breaks. Three different things get conflated. The general health rate of 14.60% is fixed in statute and has not changed since 2015. The average Zusatzbeitrag, announced by the health ministry each autumn, rose from 2.50% to 2.90% for 2026 – but it is a reference value, not a rate anybody deducts. What goes in the pay run is the rate the employee’s own Krankenkasse has set, which varies considerably from fund to fund. Since 2019 the supplement has been shared equally between employer and employee, so any guide describing it as employee-borne is years out of date.
Long-term care insurance has the most intricate rate table in German payroll, and all of the movement is on the employee side. The base rate is 3.60%, split evenly. An employee aged 23 or over with no children pays an extra 0.60 percentage points; from the second child under 25 the employee pays 0.25 points less per child, up to the fifth. The employer’s share stays at 1.80% in every case. The exception is Saxony, where the employer pays 1.30% and the employee correspondingly more, because the state kept a public holiday the rest of Germany gave up in 1995 – and the test is the place of work, not where the employee lives.
Three employer-only costs sit outside the 21%. Accident insurance through the Berufsgenossenschaft is compulsory, employer-funded in full, priced by a risk tariff against the activity, and billed in arrears against a wage report filed by 16 February – so there is no monthly accrual unless you create one. It runs from well under 1% for office work to several percent in construction. The U2 maternity levy is payable by every employer regardless of size or workforce, and foreign employers routinely omit it on the reasoning that they employ no women, which is simply wrong. U1 applies only to employers with 30 or fewer staff. Both levies are set by each Krankenkasse. Add them and a realistic all-in figure is about 25% for a small office employer and about 23% for one above 30 people – not 21%.
Germany has two contribution ceilings and they are different numbers, which is the most common structural error in foreign-run German payroll. Pension and unemployment are capped at EUR 8,450 a month, or EUR 101,400 a year. Health and long-term care are capped lower, at EUR 5,812.50 a month or EUR 69,750 a year. The pension and unemployment ceiling has been the same nationwide since 1 January 2025, so a payroll configuration still carrying a separate eastern figure is running a pre-2025 setup.
Because the two ceilings are at different levels, the employer’s effective rate steps down twice rather than once. On our office assumptions it holds at about 25.05% up to EUR 5,812.50 a month, falls to about 23.26% at EUR 7,000, to about 21.64% at EUR 8,450, and then declines continuously – about 15.68% at EUR 140,000 a year, 10.97% at EUR 200,000 and 7.32% at EUR 300,000. For an employer with more than 30 staff, and so no U1 levy, the same curve runs from 22.85% down to 6.57%.
The consequence worth putting in front of a board is that German employer social insurance is hard-capped in absolute terms. The health and care element stops at about EUR 613 a month and the pension, unemployment and levy element at about EUR 1,141, so the employer’s social insurance caps at about EUR 1,754 a month – roughly EUR 21,050 a year, or about EUR 21,950 with office accident insurance – for a small employer. An employee on EUR 110,000 and an employee on EUR 400,000 cost the employer the same in social insurance. Germany is expensive in the middle of the salary range and comparatively cheap at the top, which is the opposite of what most country pages claim.
Two practical notes on the ceilings. They are annual as well as monthly: a one-off payment such as a Christmas bonus is tested against a pro-rated annual ceiling rather than the monthly one, which is why a bonus can attract more contributions than a monthly test suggests. And the Märzklausel means one-off payments made between January and March may have to be allocated back to the previous year. Both are routine in German payroll and both are commonly missing from a system configured abroad.
Wage tax is deducted by Steuerklasse, and the class comes from the federal ELStAM database rather than from the employer. Class I covers single, divorced and widowed employees and is the default for most foreign-employer hires. Class II adds single-parent relief. Classes III and V are the married combination that lowers one spouse’s deduction and raises the other’s. Class IV is the balanced married default, with an optional factor method. Class VI applies to second and further jobs and carries no allowances at all.
Class VI is the one that generates complaints. The employer must also apply it where ELStAM cannot be retrieved at all, which happens whenever an inbound hire has no German tax identification number yet. The employee sees a punitive first payslip, the employer is blamed, and the calculation was correct throughout. The fix is to start the tax ID and, where needed, a certificate from the tax office before the first pay run rather than after the complaint.
The 2026 tariff has a tax-free allowance of EUR 12,348, a 42% rate from EUR 69,879 and a 45% rate from EUR 277,826. The solidarity surcharge is 5.5% of the wage tax, but an exemption threshold of EUR 20,350 of annual tax for a single filer removes it for the large majority of employees. Church tax is 8% of wage tax in Bavaria and Baden-Württemberg and 9% elsewhere, determined by where the employee lives, and delivered to the employer through ELStAM – the employer never asks.
One thing needs stating carefully because a lot of commercial content gets it wrong. Steuerklassen III and V have not been abolished. Replacing them is a government plan, but no abolition has been enacted with a start date, and as at September 2026 both classes remain fully in force. The factor method that would replace them is already available today on joint application.
The statutory minimum wage rose to EUR 13.90 an hour on 1 January 2026 and rises again to EUR 14.60 on 1 January 2027. Both steps are set by the same ordinance, so the 2027 figure is legislated rather than expected. Together the two steps are about 13.9%, the largest two-stage increase since the minimum wage was introduced in 2015. The independent minimum wage commission recommended them in June 2025 and the federal government made them binding by ordinance later that year.
Sector minimum wages sit above the general rate in a number of industries – among them roofing, electrical trades, painting, scaffolding, building cleaning, care, waste and temporary agency work – made binding by ordinance under the posting legislation. They override the general minimum where higher and, importantly for a foreign employer, they bind companies posting workers into Germany. Enforcement sits with customs, not with a labour inspectorate.
The Minijob threshold is not a fixed figure and has not been one since October 2022: it is the minimum wage multiplied by 130 and divided by 3, rounded up, which is ten hours a week at the minimum wage. For 2026 that is EUR 603 a month, up from EUR 556, and it moves to EUR 633 in 2027. On a commercial Minijob the employer pays flat-rate contributions of 13% for health insurance where the employee is in the statutory system, 15% for pension and optionally 2% flat-rate tax, plus the levies – all of it to the Minijob-Zentrale rather than to the employee’s own Krankenkasse.
Above the Minijob threshold sits the transition zone (Übergangsbereich), from EUR 603.01 to EUR 2,000 a month. The employee’s contributions taper up across that band from near zero to the full share, and the employer’s share is raised at the bottom of it – so it is a subsidy to the employee that the employer partly funds, not a saving for the employer. The lower limit rises every year with the minimum wage while the upper limit has stayed at EUR 2,000 since 2023, so the band narrows each year.
Dismissal protection under the Kündigungsschutzgesetz applies only where the employer has more than ten employees and the individual has more than six months’ service – both tests must be met. Below that threshold a dismissal needs no justification, which makes Germany considerably more flexible for a small operation than its reputation suggests. Above it, a dismissal must rest on conduct, capability or operational grounds, and an operational dismissal needs a social selection weighing length of service, age, maintenance obligations and disability across comparable employees. Statutory notice under §622 BGB starts at four weeks to the 15th or the end of a month and extends with service to seven months at twenty years.
There is no general statutory right to severance. Abfindung is a matter of settlement and negotiation, and the rule of thumb of half a month’s salary per year of service comes from the optional §1a route rather than from a general entitlement. Where a works council exists it must be consulted before any dismissal, and a dismissal issued without that consultation is void. Collective redundancies above the statutory thresholds must be notified to the employment agency, and the Court of Justice confirmed on 30 October 2025 that a missing or defective notification voids the dismissals and cannot be cured afterwards – when much 2024 commentary expected the rule to be relaxed.
Holiday is where foreign employers build up real balance-sheet exposure. The statutory minimum is 24 working days on a six-day week, which is 20 days on a five-day week, and market practice for a professional role is 27 to 30. The statute says leave expires at the end of the year – but European and Federal Labour Court case law has largely overridden that. Leave does not expire, and does not even become time-barred, unless the employer actively enabled the employee to take it: telling each employee individually how many days they have, by when they must be taken, and that they will otherwise be lost, in time for it to be possible. The burden of proof is on the employer. Where that is not done, untaken leave accumulates and becomes a cash payment on termination.
On working time, be precise about what exists. The Federal Labour Court held on 13 September 2022 that employers must record working time, reading the existing health and safety statute in line with EU law. That duty is real and applies now. What does not exist yet is implementing legislation: the labour ministry circulated a draft amendment to the Working Time Act in June 2026 that would require electronic recording, but it has not been adopted, so there is no statutory format and no dedicated penalty regime. Any page telling you Germany has a time-recording statute is wrong, and so is any page telling you there is no obligation.
German employer contribution rates, 2026
| Contribution | Employer | Employee | 2026 ceiling and notes |
|---|---|---|---|
| Rentenversicherung – pension | 9.30% | 9.30% | Ceiling EUR 8,450 a month, EUR 101,400 a year. The same nationwide since 2025 |
| Arbeitslosenversicherung – unemployment | 1.30% | 1.30% | Ceiling EUR 8,450 a month |
| Krankenversicherung – general rate | 7.30% | 7.30% | Ceiling EUR 5,812.50 a month, EUR 69,750 a year. Unchanged since 2015 |
| Krankenversicherung – Zusatzbeitrag | 1.45% | 1.45% | Half of the 2.90% average for 2026. Each Krankenkasse sets its own rate |
| Pflegeversicherung – base | 1.80% | 1.80% | Ceiling EUR 5,812.50 a month. The employer share is 1.80% whatever the child count |
| Pflegeversicherung – childless supplement | — | +0.60% | Employees aged 23 and over with no children |
| Pflegeversicherung – children under 25 | — | −0.25% per child | From the second child to the fifth. Employee only |
| Pflegeversicherung – Saxony | 1.30% | Correspondingly higher | The split differs in Saxony. The test is the place of work |
| Unfallversicherung – Berufsgenossenschaft | Risk-priced | — | Employer only. Set by risk tariff, billed in arrears, wage report by 16 February |
| Umlage U1 – sick pay reimbursement | Set by each fund | — | Only employers with 30 or fewer employees. Depends on the reimbursement rate chosen |
| Umlage U2 – maternity | Set by each fund | — | Every employer, regardless of size or workforce |
| Insolvenzgeldumlage | 0.15% | — | Every private-sector employer. On pension-liable pay |
| Four-branch employer subtotal | 21.15% | — | At the average Zusatzbeitrag. The figure most guides quote |
| Realistic all-in – 30 or fewer staff, office | About 25% | — | Including U1, U2, the insolvency levy and accident insurance |
| Realistic all-in – more than 30 staff, office | About 23% | — | No U1. About half a point lower in Saxony |
| Lohnsteuer | — | Per Steuerklasse | Six classes, retrieved through ELStAM. Class VI where none can be retrieved |
| Solidaritätszuschlag | — | 5.5% of Lohnsteuer | Only above EUR 20,350 of annual tax (EUR 40,700 joint) |
| Kirchensteuer | — | 8% or 9% of Lohnsteuer | 8% in Bavaria and Baden-Württemberg, 9% elsewhere. By residence |
| Minijob – employer flat rates | 13% + 15% + 2% | — | Health, pension and optional flat tax, plus levies. Threshold EUR 603 a month |
The two ceilings, and how employer cost steps down twice
| Monthly gross | Health and care | Pension and unemployment | Employer cost as % of gross |
|---|---|---|---|
| EUR 3,333 (EUR 40,000 a year) | Below the ceiling | Below the ceiling | 25.05% |
| EUR 5,812.50 (EUR 69,750 a year) | At the ceiling | Below the ceiling | 25.05% – the last full-rate euro |
| EUR 7,000 (EUR 84,000 a year) | Capped | Below the ceiling | 23.26% |
| EUR 8,450 (EUR 101,400 a year) | Capped | At the ceiling | 21.64% |
| EUR 11,667 (EUR 140,000 a year) | Capped | Capped | 15.68% |
| EUR 16,667 (EUR 200,000 a year) | Capped | Capped | 10.97% |
| EUR 25,000 (EUR 300,000 a year) | Capped | Capped | 7.32% |
Employer social insurance by salary, 2026
| Annual gross | 30 or fewer staff | % of gross | More than 30 staff | % of gross |
|---|---|---|---|---|
| EUR 40,000 | EUR 10,020 | 25.05% | EUR 9,140 | 22.85% |
| EUR 55,000 | EUR 13,778 | 25.05% | EUR 12,568 | 22.85% |
| EUR 69,750 | EUR 17,472 | 25.05% | EUR 15,938 | 22.85% |
| EUR 84,000 | EUR 19,539 | 23.26% | EUR 17,691 | 21.06% |
| EUR 101,400 | EUR 21,948 | 21.64% | EUR 19,717 | 19.44% |
| EUR 140,000 | EUR 21,948 | 15.68% | EUR 19,717 | 14.08% |
| EUR 200,000 | EUR 21,948 | 10.97% | EUR 19,717 | 9.86% |
| EUR 300,000 | EUR 21,948 | 7.32% | EUR 19,717 | 6.57% |
The cost tables assume the 2026 average Zusatzbeitrag of 2.90% – the rate that actually applies is each employee’s own Krankenkasse’s, so the real figure varies employee by employee. They assume a U1 levy of 2.2% for employers with thirty or fewer staff, a U2 levy of 0.55% and the 0.15% insolvency levy, all on pay up to the pension ceiling, and office accident insurance of 1.0% on pay up to EUR 90,000. U1 and U2 are set by each Krankenkasse and accident insurance by each Berufsgenossenschaft, so those three are working assumptions, not published rates; industrial employers pay several times the accident figure. In Saxony every figure is about half a point lower. Wage tax is excluded, as an employee cost, and so is any agreed holiday or Christmas pay. These are TopSource calculations from the 2026 rates, not published figures.
Rates, thresholds and ceilings shown are for the 2026 calendar year and were verified on 23 September 2026. The contribution ceilings and the average Zusatzbeitrag are reset each January, driven by wage growth two years earlier. Individual Krankenkassen set their own Zusatzbeitrag and can change it during the year, so the cost of a given employee can move without anything changing in the employment. The minimum wage rose to EUR 13.90 on 1 January 2026 and rises to EUR 14.60 on 1 January 2027, which moves the Minijob threshold with it. Accident insurance is priced by your Berufsgenossenschaft against your activity. A collective agreement, where one binds you, may set leave, working time and pay above every statutory minimum on this page. This page is general information, not tax or legal advice.
How our German payroll service works
Why TopSource for German Payroll
TopSource for payroll, Employer of Record or any other of our services represents a simpler, more reliable and transparent option.
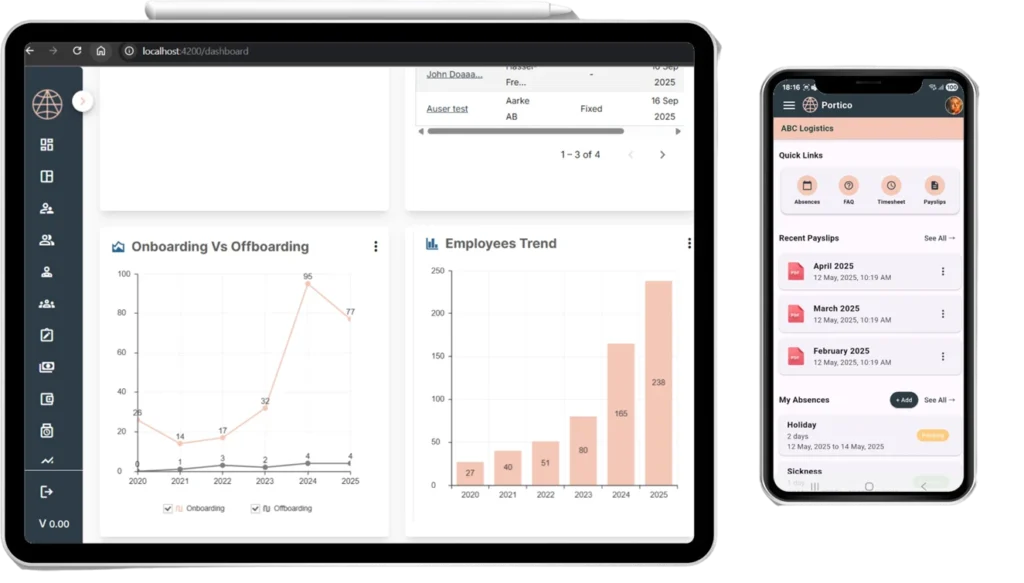
We don’t hide fees or sneak price increases. We run German payroll in-house and register you with your own Betriebsnummer rather than pooling you under a bureau’s, so the same team that files your Beitragsnachweis answers your calls. You get a named account manager, one consolidated monthly invoice covering salaries, contributions, taxes and fees, and one live Portico view of Germany beside every other country we run for you. Portico syncs with your time-tracking, leave and HR systems via API – set up by our onboarding team, not left to yours. GDPR, SOC 2 and ISO 27001 certified.
Other services
Accelerating your growth in Germany and beyond
TopSource goes far beyond payroll, acting as your end-to-end partner in global workforce management. From Employer of Record (EOR) services and seamless entity setup to localized accountancy and fractional HR support, we cover every aspect of international employment.
Meet our experts for Germany
Whether you’re entering the market or scaling operations, our specialists provide the insight and guidance you need to succeed in one of the world’s most dynamic and regulated employment landscapes. With TopSource, you’re backed by real experts, every step of the way.
Beyond a payroll serviceA globalization accelerator
Payroll platform
Global payroll simplified
Your intuitive hub for paying global teams. Simple, powerful, and designed to scale with you — no complexity, just clarity.
Audit
Eliminate barriers to growth
Avoid compliance issues across your global workforce and uncover opportunities to improve profitability. On a quarterly basis we’ll help you audit your global talent strategy to ensure it aligns with your business goals.
Intelligence
Build a data-driven talent strategy
Grow confidently and profitably with access to the latest TopSource insights & data on hiring markets, salary benchmarking & benefits.
Advisory
Expert guidance that turns complexity into clarity.
Whether you’re managing a global acquisition or entering a new market, you get clear guidance to navigate complex decisions, avoid delays, and accelerate your global expansion.
German payroll FAQs
Budget 23% to 25% of gross for a typical office employee below the contribution ceilings, not the 21% most guides quote. The four statutory branches come to 21.15% on the employer side at the 2026 average health supplement, but that figure leaves out accident insurance through the Berufsgenossenschaft, the U2 maternity levy payable by every employer regardless of size, and the 0.15% insolvency levy. Employers with 30 or fewer staff also pay the U1 sick pay levy. Above EUR 101,400 a year the employer cost stops rising, because both contribution ceilings have been passed, so the percentage falls to about 11% at EUR 200,000.
There are two ceilings and they are different numbers. Pension and unemployment insurance are capped at EUR 8,450 a month, or EUR 101,400 a year. Health and long-term care insurance are capped lower, at EUR 5,812.50 a month or EUR 69,750 a year. Because they sit at different levels, the employer’s effective rate steps down twice as salary rises – from about 25% below both, to about 23% at EUR 7,000 a month and about 22% at EUR 8,450, and then falling continuously. The pension and unemployment ceiling has been the same nationwide since 1 January 2025.
You use the rate set by each employee’s own Krankenkasse, not the national average. The general health insurance rate of 14.60% is fixed in statute and has not changed since 2015. The average Zusatzbeitrag, announced by the health ministry each autumn, rose from 2.50% to 2.90% for 2026 – but it is a reference value, not a rate anyone deducts. What goes in the pay run is the individual fund’s own rate, which varies considerably between funds, so an employer with forty staff may be applying a dozen different rates at once. Since 2019 the supplement has been shared equally between employer and employee.
Before the month they relate to has ended. The total social insurance contribution must be in cleared funds with each employee’s Krankenkasse on the third-to-last banking day of the month in which the work is performed, with the contribution statement filed two working days before that. Because the month has not finished when payment falls due, the amount is estimated and any difference is settled the following month. Wage tax runs on a separate calendar – monthly, quarterly or annually by the 10th, according to the previous year’s total – so German payroll has two unrelated payment cycles.
The statutory minimum wage is EUR 13.90 an hour from 1 January 2026, rising to EUR 14.60 from 1 January 2027. Both steps were set by the same ordinance, so the 2027 figure is already legislated rather than expected. Together they are about 13.9%, the largest two-stage rise since the minimum wage was introduced in 2015. Sector minimum wages in industries such as building cleaning, care and several construction trades run above the general rate and override it, and they bind foreign employers posting workers into Germany.
The employer pays Entgeltfortzahlung for up to six weeks per illness at 100% of normal pay, once the employee has completed four weeks of service. From week seven the employee’s Krankenkasse pays Krankengeld at a lower rate. Sick certificates are electronic: the employer retrieves the eAU from the Krankenkasse rather than receiving a paper note, so the duty to pull the record sits with payroll. Employers with 30 or fewer employees recover part of the six weeks through the U1 levy, at a reimbursement rate chosen with the fund.
Yes, but no statute yet says how. The Federal Labour Court held on 13 September 2022 that employers must record working time, reading the existing health and safety legislation in line with EU law, and that obligation applies now. What does not exist is implementing legislation: the labour ministry circulated a draft amendment to the Working Time Act in June 2026 that would require electronic recording, but it has not been adopted. So there is no prescribed format and no dedicated penalty regime yet. Any source stating that Germany has a time-recording statute is wrong, and so is any source stating that there is no obligation.
A Minijob is employment below the earnings limit (Geringfügigkeitsgrenze), which for 2026 is EUR 603 a month. The threshold is not fixed: since October 2022 it has been the minimum wage multiplied by 130 and divided by 3, rounded up – ten hours a week at the minimum wage – so it rises to EUR 633 in 2027. On a commercial Minijob the employer pays flat-rate contributions of 15% for pension, 13% for health insurance where the employee is in the statutory system and optionally 2% flat-rate tax, plus the levies. All of it goes to the Minijob-Zentrale rather than to the employee’s own Krankenkasse.
Statutory notice under §622 BGB is four weeks to the 15th or the end of a calendar month during the first two years, extending with service to one month at two years, two months at five, three at eight, four at ten, five at twelve, six at fifteen and seven months at twenty years, always to the end of a month. A probationary period of up to six months may be agreed with two weeks’ notice. Collective agreements and contracts often lengthen these, and a contract may not give the employee a longer notice period than the employer. Dismissal protection under the Kündigungsschutzgesetz is separate and applies only where the employer has more than ten employees and the individual more than six months’ service.
Yes, but the tax and social insurance answers are opposite, and that asymmetry is the most important thing to understand. Social insurance is unavoidable: work performed in Germany brings German social insurance law with it, so a foreign employer must obtain a Betriebsnummer, appoint an authorised representative in Germany, and calculate and remit contributions to each employee’s Krankenkasse. Wage tax is the reverse: §38 EStG attaches the withholding duty to an employer with a German permanent establishment, so without one there is no duty to withhold. That is not a saving – it moves a self-assessment and tax prepayments onto the employee, which is why many foreign employers withhold voluntarily or use an Employer of Record.
Looking at other markets too?
We help organizations employ and pay teams in 164 countries.