Payroll Services in Sweden
Fully managed Swedish payroll – arbetsgivaravgifter and ITP1 applied on the right side of the SEK 52,125 line each month rather than annualised, karensavdrag calculated as 20% of a week rather than as a day, and the arbetsgivardeklaration filed on your date with the money on Skatteverket’s account on time, with a named specialist a phone call away.

TopSource rated 5/5 by our customers
What Swedish payroll actually involves
Swedish payroll looks simple and is governed in two layers, only one of which is law. The statutory layer is genuinely straightforward: one contribution rate of 31.42% with no ceiling, one monthly declaration filed per employee, one tax account through which everything settles, and a preliminary tax table assigned by Skatteverket according to where the employee lives. The second layer is the collective agreement, and it sets the things that actually decide cost – the pension, the insurances, the holiday pay, the number of leave days, the notice periods and the parental pay top-up. There is no statutory minimum wage in Sweden at all; the floor comes from the agreement. Collective agreements cover 88% of employees, an employer can lawfully operate without one and very few successfully do, and the pension premium inside that second layer steps from 4.5% to 30% at a single monthly threshold. Almost every expensive mistake in Swedish payroll comes from treating the first layer as the whole picture.
Our Partners Globally




Calculate Your Employee Costs in Sweden
Enter a gross annual salary to see the statutory employer contributions for a Swedish employee: arbetsgivaravgifter of 31.42% on all pay, with no ceiling. The calculator does not add the ITP1 occupational pension and insurances that come with a collective agreement, which with särskild löneskatt add about 6.3% on pay up to SEK 52,125 a month and about 39.6% on pay above it – the cost table below shows the full figure – or the reduced rates for employees aged 19 to 23 or 67 and over.
Employment Cost Calculator
*Indicative figures only and not definitive legal advice. Local regulations change frequently. Consult an expertSweden
| British Pound | Sweden | |
|---|---|---|
| Base Salary (per month) | ||
| Employer Contributions | ||
| Total Cost (Annual) | ||
| Total Cost (Monthly) |
“Their expertise and understanding of the unique hiring, payment, and human resource practices in each country has been nothing short of outstanding. Our Client Success Manager, has done just that … ensured our success. Her availability and willingness to engage on a personal level has made all the difference.”
“Excellent service, especially from our account manager who has gone above and beyond to help us use the platform effectively. Our manager, significantly simplifies my workload. It is like having your own TopSource HR representative on your team.”
“TopSource has been our go-to resource for international hiring. They are responsive, thorough, respectful and knowledgeable. The Client Success team has provided us with the utmost customer service, and the more we use TopSource, the more, it gives us access to more resources and knowledge.”
Employer Costs in Sweden Explained
A Swedish employee costs an employer about 37.7% above salary below SEK 52,125 a month and about 71.0% above it – not the 31.42% that almost every country guide quotes. Arbetsgivaravgifter are 31.42% of all pay with no ceiling at any salary, made up of 18.80% of social insurance contributions plus a 12.62% allmän löneavgift that is a pure tax. On top of that, a white-collar employee on ITP1 carries 5.17% of collectively agreed pension and insurance premiums below 7.5 income base amounts and 31.94% on the excess above it, because the retirement premium alone steps from 4.50% to 30.00%. Then särskild löneskatt adds 24.26% on the pension premiums, another 1.13 points below the line and 7.65 above it. The collectively agreed layer is not law, but it covers 88% of Swedish employees and no employer that wants to recruit goes without it. Here’s the breakdown.
Arbetsgivaravgifter are 31.42% of pay in 2026, with no ceiling at any salary level, and that is not what employing someone in Sweden costs. The 31.42% is two things stacked: 18.80% of social insurance contributions under Socialavgiftslagen (2000:980) – 10.21% old-age pension, 3.55% sickness insurance, 2.64% labour market, 2.00% parental insurance, 0.30% survivors’ pension and 0.10% work injury – and then 12.62% of allmän löneavgift under Lag (1994:1920), which is a pure tax rather than an insurance contribution. The allmän löneavgift works as the balancing item, which is why the headline has held at 31.42% while the components beneath it moved.
Above that sits the collectively agreed layer, and it is not optional in any practical sense. Occupational pension and the associated insurances are not law – they come from the agreement between Svenskt Näringsliv and PTK for white-collar staff, and between Svenskt Näringsliv and LO for blue-collar – but they cover 88% of Swedish employees and no employer that wants to recruit will go without them. For a white-collar employee on ITP1 they add 5.17% below the ceiling and 31.94% above it, and there is a third layer behind that: särskild löneskatt på pensionskostnader at 24.26%, charged on the employer’s pension premiums rather than on salary.
The honest all-in figures are therefore about 37.7% below the ceiling and about 71.0% above it, and the second number is the one that surprises people. Blue-collar equivalents under Avtalspension SAF-LO are about 37.4% and 68.7%. Särskild löneskatt is the part most often left out of a model entirely, because it is not a payroll-cycle payment at all: a limited company reports it on its annual income tax return and settles it through the tax account. Collectum and Alecta publish their premiums excluding it, so an ITP1 premium of 30% actually costs 30% multiplied by 1.2426, which is 37.3%.
Three reductions can lower the statutory rate and all of them have conditions. A temporary rate of 20.81% applies to employees aged 19 to 23 on pay up to SEK 25,000 a month from 1 April 2026 to 30 September 2027 – it is explicitly temporary and should not be built into a medium-term model. Employees aged 67 and over at the start of the year pay 10.21%, the threshold having moved from 66 on 1 January 2026. And växa-stöd gives a first or second employee 10.21% on pay up to SEK 35,000 a month for up to 24 months, but from January 2026 it is claimed as a refund after paying in full rather than applied as a reduced rate.
The single most important number in Swedish employer cost is 7.5 income base amounts – SEK 625,500 a year, or SEK 52,125 a month in 2026. Below that line the ITP1 retirement premium is 4.50% of salary. Above it, on the excess only, it is 30.00%. That is a 6.7-times step in the main component and a 6.2-times step in the total collectively agreed cost, from 5.17% to 31.94%, and because arbetsgivaravgifter are uncapped and särskild löneskatt applies to the pension premiums, the employer’s marginal cost on salary above the line is roughly 71% against roughly 37.7% below it – a step of 33.3 percentage points at one threshold.
The 30% is not a bonus and it is not arbitrary. Income above 7.5 income base amounts earns no further state income pension, so the collectively agreed scheme contributes 30% above the line precisely to replace the public accrual that stops there. The upper limit is 30 income base amounts – SEK 2,502,000 a year, or SEK 208,500 a month – above which no ITP1 premium is due at all. Worth stating plainly for a budget: SEK 100,000 of additional salary below the line costs the employer about SEK 137,700, and the same SEK 100,000 above it costs about SEK 171,000.
The threshold is applied per month, not per year, and this is where payroll systems go wrong. It is the annual income base amount divided by twelve, tested against that month’s pay. So a one-off bonus, a commission payment or a holiday pay lump sum that pushes a single month above SEK 52,125 triggers the 30% premium on the excess for that month, even where the employee’s annual salary is comfortably below the annual equivalent. Systems configured to annualise, or to test base salary only, understate the premium in bonus months – Collectum then invoices the correct higher amount and the accrual will not reconcile.
There is a band where this happens to everybody and nobody expects it. The semestertillägg – 0.43% of monthly salary per vacation day, so 10.75% of a month’s pay across 25 days – is normally paid in one month. For an employee on a base salary between about SEK 564,800 and SEK 625,500 a year, every ordinary month is below the ceiling but the holiday month is not. On a SEK 600,000 salary that is about SEK 3,250 of excess in a single month and roughly SEK 1,080 of extra employer cost, which a payroll applying the threshold annually records as zero. ITP2, which applies to white-collar employees born in 1978 or earlier, is a different problem again: it is defined benefit, individually calculated on salary, age and previously earned pension, and it can run well above 30% of salary for someone in their late fifties. Budget ITP2 from the Collectum invoice history, never from a rate card.
Swedish employers report per employee, every month. The arbetsgivardeklaration på individnivå replaced the annual kontrolluppgift for employment income in 2019, so Skatteverket and Försäkringskassan receive individual income data in near real time, and the employee can see month by month what has been reported for them. The practical consequence is that errors are visible immediately and are corrected at period level by refiling that period – not tidied up in a December adjustment, because there is no longer a December adjustment.
The deadlines split at SEK 40 million of turnover, and the split catches growing companies. Below it, filing and payment are both due on the 12th of the month following the pay month, or the 17th in January and August. Above it, the declaration is due on the 26th – but the deducted tax and arbetsgivaravgifter must still be on Skatteverket’s account by the 12th. A company that crosses the threshold, correctly moves its filing to the 26th and reasonably moves its payment with it runs a skattekonto deficit from the 12th every single month, quietly accruing kostnadsränta.
Everything settles through one account, and that is both the convenience and the trap. Deducted tax, arbetsgivaravgifter, VAT, corporate preliminary tax and any penalties all run through the skattekonto. Because it nets, a VAT refund can mask a payroll tax shortfall for months before anyone notices, and a deficit accrues interest and can end up with Kronofogden, which creates a public payment record. Reconciling the skattekonto monthly rather than annually is standard Swedish practice for exactly this reason.
Two things about corrections are worth knowing before you need them. A correction that increases the liability for an earlier period generates kostnadsränta from that period’s original due date, not from the date of the correction. But skattetillägg – the penalty for incorrect information – is not charged where the employer corrects voluntarily before Skatteverket raises the issue. So finding an error in your own declaration and refiling it removes the penalty exposure, though not the interest, and it is worth building a monthly reconciliation that would actually find it.
Annual leave is 25 days under Semesterlagen (1977:480), on a holiday year normally running 1 April to 31 March, earned in the twelve months before. That timing means a new joiner has the right to take 25 days in year one but many of them will be unpaid, which is why many agreements and contracts grant förskottssemester – advance holiday that can be clawed back if the employee leaves within five years. Employees are entitled to four consecutive weeks between June and August unless otherwise agreed.
Holiday pay has two calculation methods and choosing the wrong one is one of the most expensive recurring errors in Swedish payroll. Sammalöneregeln, the default for monthly-paid staff, keeps the ordinary salary and adds a semestertillägg of 0.43% of monthly salary per day taken – 10.75% of a month’s pay over 25 days, roughly 0.9% of annual salary. Procentregeln pays 12% of total earned pay in the earning year and must be used where pay is variable. The trap is the employee whose pattern changes mid-year: where hours changed during the earning year the monthly salary has to be adjusted, and where the variable element became material, procentregeln applies instead. The error repeats annually and compounds. And the statute is only the floor: white-collar agreements commonly pay a higher semestertillägg and more than 25 days.
Sick pay is the employer’s for fourteen calendar days at 80%, less the karensavdrag of 20% of a normal week’s sick pay. Two rules decide whether a system gets it right. The återinsjuknanderegel says that if the employee returns and falls ill again within five calendar days it is legally the same sickness period – no new karensavdrag, and the fourteen-day clock continues rather than restarting. And the general reimbursement for high sick pay costs was abolished on 1 July 2024; only särskilt högriskskydd remains, for an individual employee with an approved condition. Many country guides still describe the old scheme.
Parental leave is 480 days per child from Försäkringskassan, 390 at the income-related rate with 90 reserved for each parent, on income capped at ten price base amounts – SEK 592,000, giving a maximum of about SEK 1,259 a day. The employer’s own obligations under Föräldraledighetslagen (1995:584) are the right to leave, the right to reduce hours by up to 25% until the child is eight, and a strict prohibition on disadvantaging an employee for reasons connected to parental leave – a pay review that skips someone on leave is a classic breach. Then there is föräldralön, the collectively agreed top-up, which is standard rather than exceptional: typically 10% of salary up to the ceiling and around 90% of salary on the portion above it, where the State pays nothing. For a senior employee that top-up is borne almost entirely by the employer, and it is the part foreign budgets miss.
The LAS reform of 1 October 2022 changed the economics of a Swedish dismissal more than the test for one. The standard was reworded from saklig grund to sakliga skäl, focused on whether the employee breached the contract, with redeployment still required. The change that actually matters is different: employment no longer continues during a dispute. Before the reform, a challenged dismissal kept the employee employed and paid until the court ruled, often for more than a year. Now the employment ends when notice expires even if the dismissal is challenged, and the employee claims damages if successful. That removed the main source of settlement leverage employees had.
Redundancy selection follows length of service within each turordningskrets – last in, first out – and the reform lets every employer, regardless of size, exempt three employees as being of special importance. Fixed-term contracts became särskild visstidsanställning, converting to permanent after more than twelve months within a five-year period. Statutory notice runs from one month below two years’ service to six months at ten years or more, with the employee giving one month regardless – and collective agreements frequently lengthen all of it.
Two things survive a dismissal and both catch employers out. Företrädesrätt gives a redundant employee priority for re-employment for nine months from the end of employment where they had more than twelve months’ service in the last three years and claim the right – so recruiting into that role within nine months is a live risk. And large parts of LAS, including the selection rules, can be displaced by collective agreement, and most sector agreements do vary them. The statutory position is rarely the operative one.
For a foreign employer two further rules decide whether Sweden is in scope at all. Since 1 January 2021 Sweden applies the economic employer concept: where an employee is effectively hired out to a Swedish business that directs and benefits from the work, the 183-day rule no longer applies and the employee is taxable in Sweden from day one, subject only to a de minimis of no more than 15 consecutive working days at a time and 45 working days in a calendar year. It applies to intra-group secondments, not just third-party staffing. Separately, a foreign employer without a permanent establishment may enter a socialavgiftsavtal under which the employee takes over reporting and paying the contributions – which removes the employer’s Swedish reporting burden and transfers real administrative risk onto the individual.
Swedish employer contribution rates, 2026
| Contribution | Employer | Employee | Applies to |
|---|---|---|---|
| Sjukförsäkringsavgift – sickness insurance | 3.55% | — | All pay. No ceiling at any salary |
| Föräldraförsäkringsavgift – parental insurance | 2.00% | — | All pay |
| Ålderspensionsavgift – old-age pension | 10.21% | — | All pay |
| Efterlevandepensionsavgift – survivors’ pension | 0.30% | — | All pay |
| Arbetsmarknadsavgift – labour market | 2.64% | — | All pay |
| Arbetsskadeavgift – work injury | 0.10% | — | All pay |
| Subtotal, Socialavgiftslagen | 18.80% | — | Social insurance contributions |
| Allmän löneavgift – general payroll tax | 12.62% | — | Lag (1994:1920). A pure tax, not an insurance contribution |
| Total arbetsgivaravgifter | 31.42% | — | Unchanged for 2026. No ceiling |
| Reduced rate, 67 or over at the start of the year | 10.21% | — | Born 1938 to 1958. The age threshold moved from 66 to 67 on 1 January 2026 |
| Reduced rate, born 1937 or earlier | 0% | — | No contributions |
| Youth rate, aged 19 to 23 | 20.81% | — | On pay up to SEK 25,000 a month. In force 1 April 2026 to 30 September 2027 |
| ITP1 retirement, to SEK 52,125 a month | 4.50% | — | Collectively agreed, not statutory. White-collar born 1979 or later |
| ITP1 retirement, above SEK 52,125 a month | 30.00% | — | On the excess only, up to SEK 208,500 a month |
| ITP1 associated insurances | 0.67% / 1.94% | — | Premium waiver, ITP sjukpension, TGL, TFA and transition support, below / above the ceiling |
| Avtalspension SAF-LO, blue-collar | 4.50% / 30.00% | — | Below / above SEK 52,125 a month, under the agreement with LO |
| Särskild löneskatt på pensionskostnader | 24.26% | — | On the pension premiums, not on salary. Not paid through the payroll |
| Preliminary A-tax | — | Per skattetabell | Set by municipality of residence, age and congregation membership. 30% flat on a second job |
| SINK – non-residents | — | 22.5% | Flat final tax in 2026, falling to 20% on 1 January 2027 |
The step at 7.5 income base amounts – SEK 52,125 a month
| Cost component | To SEK 52,125 a month | Above SEK 52,125 a month | Note |
|---|---|---|---|
| Arbetsgivaravgifter | 31.42% | 31.42% | No ceiling. This is the part that makes the step so large |
| ITP1 retirement premium | 4.50% | 30.00% | On the excess only. A 6.7-times step at one line |
| Premiebefrielseförsäkring | 0.125% | 1.415% | Premium waiver during sickness |
| ITP sjukpension | 0.030% | 0.108% | Disability pension. Its own threshold is ten price base amounts |
| TGL – group life | 0.09% | 0% | SEK 32 per employee per month in 2026 |
| TFA – work injury | 0.02% | 0.02% | Collectively agreed work injury cover |
| Omställningsstöd / AGE (TRR) | 0.40% | 0.40% | Transition support on redundancy |
| ITP1 and insurances, total | 5.17% | 31.94% | As published by Avtalat, excluding särskild löneskatt |
| Särskild löneskatt at 24.26% | about 1.13% | about 7.65% | On the pension premiums: 4.655% and 31.523% of salary |
| Total employer on-cost | about 37.7% | about 71.0% | A step of 33.3 percentage points at SEK 52,125 a month |
| Blue-collar equivalent, SAF-LO | about 37.4% | about 68.7% | AGS and föräldrapenningtillägg are at 0% in 2026 – contingent, not permanent |
| Statutory minimum wage | None | None | No statute sets one. Pay floors come from collective agreements |
Employer cost of a white-collar employee on ITP1 by base salary, 2026
| Annual base salary | Cash pay | Arbetsgivaravgifter | ITP1 and insurances | Särskild löneskatt | Total employer cost | Above base |
|---|---|---|---|---|---|---|
| SEK 420,000 | SEK 423,763 | SEK 133,146 | SEK 21,909 | SEK 4,786 | SEK 583,603 | 39.0% |
| SEK 600,000 | SEK 605,375 | SEK 190,209 | SEK 32,168 | SEK 7,048 | SEK 834,800 | 39.1% |
| SEK 750,000 | SEK 756,719 | SEK 237,761 | SEK 74,250 | SEK 17,099 | SEK 1,085,828 | 44.8% |
| SEK 900,000 | SEK 908,063 | SEK 285,313 | SEK 122,589 | SEK 28,673 | SEK 1,344,637 | 49.4% |
| SEK 1,200,000 | SEK 1,210,750 | SEK 380,418 | SEK 219,267 | SEK 51,821 | SEK 1,862,256 | 55.2% |
| SEK 1,800,000 | SEK 1,816,125 | SEK 570,626 | SEK 412,624 | SEK 98,117 | SEK 2,897,492 | 61.0% |
| SEK 2,600,000 | SEK 2,623,292 | SEK 824,238 | SEK 631,692 | SEK 150,569 | SEK 4,229,791 | 62.7% |
Arbetsgivaravgifter are statutory and apply to every employer. The pension and insurance lines are collectively agreed rather than legislated: they come from the ITP agreement between Svenskt Näringsliv and PTK for white-collar staff and from the SAF-LO agreement with LO for blue-collar, and apply to an employer that has signed a collective agreement or a hängavtal. Särskild löneskatt is charged on the employer’s pension premiums and settled through the tax return rather than the payroll, so it will not appear on a payroll report at all. The cost table assumes a white-collar employee born in 1979 or later: twelve monthly salaries plus a semestertillägg of 25 days at 0.43% paid in one month, arbetsgivaravgifter at 31.42%, ITP1 at 5.17% up to SEK 52,125 a month and 31.94% on the excess, tested month by month, and särskild löneskatt on the pension premiums. It excludes sick pay, föräldralön, holiday terms above the statutory minimum and the reduced rates for younger and older employees, and ITP2 for employees born in 1978 or earlier costs more. These are TopSource calculations from the 2026 rates, not published figures.
Rates, thresholds and base amounts shown are for the 2026 calendar year and were verified on 22 September 2026. The income base amount and the price base amount are set by the government each autumn and move on 1 January, which moves the SEK 52,125 pension threshold, the SEK 592,000 benefit ceiling and every figure derived from them. Collectively agreed premiums are also announced each autumn; for 2026, AGS and föräldrapenningtillägg are at 0%. The reduced rate for employees aged 19 to 23 is temporary and expires on 30 September 2027, and SINK falls from 22.5% to 20% on 1 January 2027. Your collective agreement may set holiday pay, leave, notice and parental pay above every statutory minimum on this page. This page is general information, not tax or legal advice.
How our Swedish payroll service works
Why TopSource for Swedish Payroll
TopSource for payroll, Employer of Record or any other of our services represents a simpler, more reliable and transparent option.
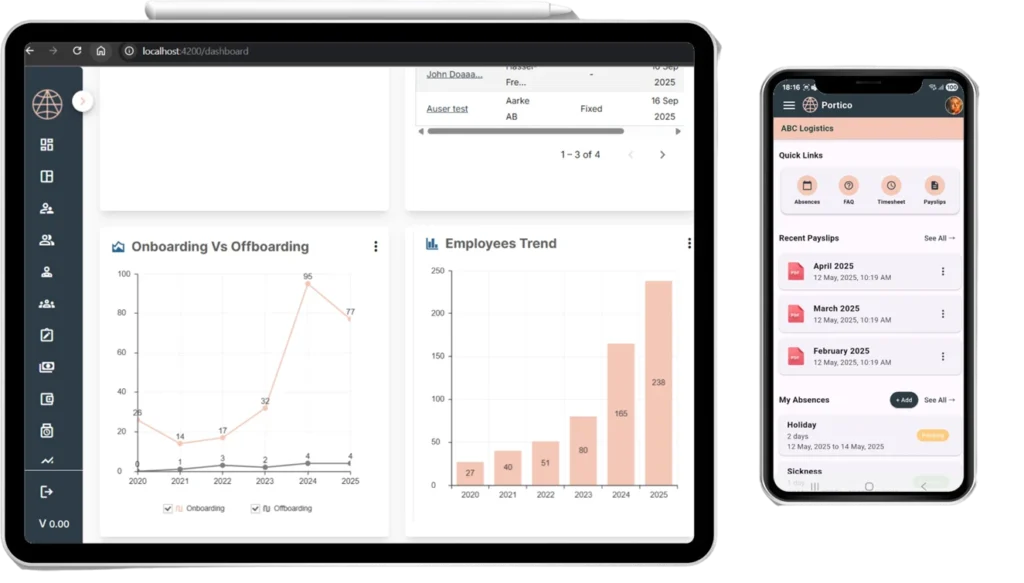
We don’t hide fees or sneak price increases. We run Swedish payroll in-house and register you with Skatteverket in your own name rather than pooling you under a bureau, so the same team that files your arbetsgivardeklaration answers your calls. You get a named account manager, one consolidated monthly invoice covering salaries, contributions, taxes and fees, and one live Portico view of Sweden beside every other country we run for you. Portico syncs with your time-tracking, leave and HR systems via API – set up by our onboarding team, not left to yours. GDPR, SOC 2 and ISO 27001 certified.
Other services
Accelerating your growth in Sweden and beyond
TopSource goes far beyond payroll, acting as your end-to-end partner in global workforce management. From Employer of Record (EOR) services and seamless entity setup to localized accountancy and fractional HR support, we cover every aspect of international employment.
Meet our experts for Sweden
Whether you’re entering the market or scaling operations, our specialists provide the insight and guidance you need to succeed in one of the world’s most dynamic and regulated employment landscapes. With TopSource, you’re backed by real experts, every step of the way.
Beyond a payroll serviceA globalization accelerator
Payroll platform
Global payroll simplified
Your intuitive hub for paying global teams. Simple, powerful, and designed to scale with you — no complexity, just clarity.
Audit
Eliminate barriers to growth
Avoid compliance issues across your global workforce and uncover opportunities to improve profitability. On a quarterly basis we’ll help you audit your global talent strategy to ensure it aligns with your business goals.
Intelligence
Build a data-driven talent strategy
Grow confidently and profitably with access to the latest TopSource insights & data on hiring markets, salary benchmarking & benefits.
Advisory
Expert guidance that turns complexity into clarity.
Whether you’re managing a global acquisition or entering a new market, you get clear guidance to navigate complex decisions, avoid delays, and accelerate your global expansion.
Swedish payroll FAQs
Budget about 37.7% on top of salary below SEK 52,125 a month and about 71.0% above it, not the 31.42% headline. Arbetsgivaravgifter are 31.42% of all pay with no ceiling, but a white-collar employee on ITP1 also carries 5.17% of collectively agreed pension and insurance premiums below the ceiling and 31.94% above it, plus särskild löneskatt at 24.26% charged on the pension premiums. Blue-collar equivalents are about 37.4% and 68.7%. The collectively agreed layer is not law, but it covers 88% of Swedish employees and no employer that wants to recruit goes without it.
Särskild löneskatt på pensionskostnader is a 24.26% tax on an employer’s pension costs, charged under Lag (1991:687), and it is not paid through the payroll cycle at all. A limited company reports the base on its annual income tax return and settles it through the tax account, so it appears in the ledger as a monthly accrual rather than as a payroll payment. It is the hidden multiplier on the pension premium: Collectum and Alecta publish their rates excluding it, so an ITP1 premium of 30% above the ceiling actually costs 30% multiplied by 1.2426, which is 37.3%.
Sweden has no statutory minimum wage – no legislation sets a pay floor of any kind. Wage floors are set by collective agreements negotiated sector by sector between employer federations and unions, which is the Swedish model. Collective agreement coverage is 88% of employees – 100% in the public sector and 83% in the private. An employer without an agreement has no wage benchmark, may face lawful industrial action to make it sign, and will still be expected to match the pension and insurance package to recruit.
It depends on turnover, and the filing date and the payment date are not always the same. Employers with turnover up to SEK 40 million file the arbetsgivardeklaration and pay on the 12th of the month following the pay month, or the 17th in January and August. Employers above SEK 40 million file on the 26th but must still have the deducted tax and arbetsgivaravgifter on Skatteverket’s account by the 12th. Payment must be received, not merely initiated, by the deadline, and a deficit on the skattekonto accrues kostnadsränta.
ITP1 is the defined-contribution occupational pension for white-collar employees born in 1979 or later, agreed between Svenskt Näringsliv and PTK and administered by Collectum. The employer pays 4.50% of salary up to 7.5 income base amounts – SEK 52,125 a month in 2026 – and 30.00% on the excess above that, up to 30 income base amounts, which is SEK 208,500 a month. The 30% exists because income above 7.5 income base amounts earns no further state pension. The threshold is tested monthly rather than annually, so a bonus that pushes a single month over the line triggers 30% on the excess for that month.
Sweden has two lawful methods and the right one depends on the employee’s pay pattern. Under sammalöneregeln, the default for monthly-paid staff, the employee keeps their ordinary salary during leave and receives a semestertillägg of 0.43% of monthly salary per vacation day – 10.75% of a month’s pay across 25 days. Under procentregeln, required where pay is variable, holiday pay is 12% of the employee’s total earned pay in the earning year. Where hours changed during the earning year the monthly salary has to be adjusted, and collective agreements often pay more than the statutory minimum.
The employer pays the first fourteen calendar days of each sickness spell at 80% of the pay the employee would have received, less a karensavdrag; from day 15 Försäkringskassan pays sjukpenning. Since 1 January 2019 the karensavdrag is 20% of the sick pay the employee would receive in an average calendar week – not one day’s pay, which is only coincidentally the same figure on an even five-day week. If the employee falls ill again within five calendar days it is legally the same spell, so there is no new karensavdrag and the fourteen-day period continues. The general reimbursement for high sick pay costs was abolished on 1 July 2024.
Yes. A foreign company can register with Skatteverket as an employer and run compliant Swedish payroll without a permanent establishment, deducting preliminary tax on pay for work performed in Sweden, paying arbetsgivaravgifter and filing the monthly arbetsgivardeklaration. A Swedish bank account is not required, though payments from abroad take longer and it is the date the money reaches Skatteverket that counts. Without a permanent establishment, a socialavgiftsavtal is also possible, under which the employee takes over reporting and paying the contributions – removing the employer’s reporting burden and transferring real administrative risk to the individual.
A samordningsnummer is the coordination number Skatteverket issues to someone who works in Sweden but does not qualify for a personnummer, typically because they will stay under twelve months, and it gates an entire Swedish payroll. Without it the employee cannot be reported correctly in the arbetsgivardeklaration, cannot receive a preliminary A-tax decision – so the employer must deduct 110% of the table amount – and cannot be registered with Collectum or Fora, so pension premiums accrue as a liability that cannot be allocated to anybody. Start the application before day one.
Statutory minimum notice from the employer under LAS runs from one month for less than two years’ service, to two months at two to four years, three at four to six, four at six to eight, five at eight to ten and six months at ten years or more; the employee gives one month regardless of service. Salary and benefits run throughout notice. Collective agreements frequently lengthen these periods, and large parts of LAS can be displaced by agreement. Since the 2022 reform the employment ends when notice expires even where the dismissal is challenged.
Looking at other markets too?
We help organizations with employ and pay teams in over 180 countries.