Payroll Services in Italy
Fully managed Italian payroll: INPS contributions, IRPEF withholding, TFR severance and the rules of every collective agreement applied on each payslip, with a named specialist a phone call away.

TopSource rated 5/5 by our customers
What a payroll company in Italy handles for you
Payroll in Italy combines INPS social security, income tax withheld at source, a severance fund that grows every month and the pay rules of the national collective agreement (CCNL) that covers each employee. The 2026 Budget Law added new flat taxes on pay rises and allowances, and from 1 July 2026 first-time employees join a pension fund automatically.
Our Partners Globally




Calculate Your Employee Costs in Italy
Enter a gross annual salary (RAL), including the 13th month, to see the employer’s cost in Italy for 2026: INPS contributions at about 30% for a typical services company and the TFR severance accrual.
Employment Cost Calculator
*Indicative figures only and not definitive legal advice. Local regulations change frequently. Consult an expertItaly
| British Pound | Italy | |
|---|---|---|
| Base Salary (per month) | ||
| Employer Contributions | ||
| Total Cost (Annual) | ||
| Total Cost (Monthly) |
“Their expertise and understanding of the unique hiring, payment, and human resource practices in each country has been nothing short of outstanding. Our Client Success Manager, has done just that … ensured our success. Her availability and willingness to engage on a personal level has made all the difference.”
“Excellent service, especially from our account manager who has gone above and beyond to help us use the platform effectively. Our manager, significantly simplifies my workload. It is like having your own TopSource HR representative on your team.”
“TopSource has been our go-to resource for international hiring. They are responsive, thorough, respectful and knowledgeable. The Client Success team has provided us with the utmost customer service, and the more we use TopSource, the more, it gives us access to more resources and knowledge.”
Employer Costs in Italy Explained
An Italian employee costs about 37% on top of gross annual salary in INPS contributions and TFR severance, before INAIL accident insurance and any extras in the collective agreement. The exact figure depends on the sector, the company’s size and the employee’s category. Here’s the breakdown.
The pension contribution (IVS) is 33% of pay: 23.81% from the employer and 9.19% from the employee, who pays an extra 1% on pay above €56,224 a year in 2026. For employees first insured from 1996, pension contributions stop at €122,295 a year. Employers also pay unemployment insurance (NASpI) at 1.31%, with an extra 1.4% on fixed-term contracts that rises by 0.5 points at each renewal, and contributions for family allowances, maternity, sickness and wage guarantee funds that depend on the sector, headcount and job category.
In all, the employer usually pays about 30% of gross pay, and the employee 9.19% or a little more where wage guarantee funds apply. Contributions are declared to INPS every month through UniEmens and paid with the F24 form by the 16th of the following month. INAIL accident insurance is paid separately, at the rate of the employer’s risk tariff.
The employer is the withholding agent (sostituto d’imposta): it deducts IRPEF from each salary at 23% on income up to €28,000, 33% from €28,000 to €50,000 and 43% above, after the employee’s tax credits, plus regional and municipal surtaxes that depend on where the employee lives. The 2026 Budget Law cut the middle rate from 35% to 33%.
It also added flat taxes applied through payroll in 2026: 5% on pay rises from collective agreements renewed between 2024 and 2026, for private-sector employees who earned up to €33,000 in 2025; 15% on night, holiday and shift allowances up to €1,500, for those who earned up to €40,000; and 1% on productivity bonuses up to €5,000. Electronic meal vouchers are now tax free up to €10 a day.
Under article 2120 of the Civil Code, every employee accrues TFR (trattamento di fine rapporto): each year, annual pay divided by 13.5, about 7.41%. Apart from the current year’s accrual, the fund is revalued every 31 December by 1.5% plus 75% of ISTAT inflation, and it is paid when employment ends, for any reason. After eight years of service, employees can ask for an advance of up to 70% for medical costs or a first home.
From 1 July 2026, private-sector employees hired for the first time join the pension fund of their collective agreement automatically, with their whole TFR, unless within 60 days they choose to keep it with the employer or send it to another fund. Employers with 50 or more employees pay the TFR that stays with them into the INPS Treasury Fund; since January 2026 this also covers employers that reach 50 after their first year (60 in 2026 and 2027), and from 2032 the threshold is 40.
For an office employee at a services company on €3,000 a month, paid 13 times a year, the gross annual salary (RAL) is €39,000. The employer pays about €11,700 in INPS contributions (30%) and accrues €2,888.89 of TFR: €14,588.89 a year, an annual cost of €53,588.89, or about 37.4% on top of salary, before INAIL accident insurance.
The employee pays €3,584.10 of INPS pension contributions (9.19%), and IRPEF and the surtaxes are withheld from the rest, after tax credits. Most collective agreements pay the 13th month (tredicesima) in December, and some, such as commerce, add a 14th month in the summer: include it in the annual salary.
Normal working time is 40 hours a week, and average weekly hours, overtime included, cannot exceed 48 over four months unless a collective agreement extends the period. Without a collective agreement, overtime needs the employee’s agreement and is capped at 250 hours a year. Employees are entitled to at least four weeks of paid holiday a year, which cannot be paid out instead of taken except when employment ends.
Mothers stop work two months before the expected birth and three months after, five months in all, paid at 80%, and fathers take ten working days at full pay between two months before and five months after the birth. Each parent can then take parental leave until the child turns 14, with up to three months between them at 80% until the child turns six and most of the rest at 30%. Probation, notice and sick pay top-ups are set by the collective agreement.
Italian payroll contributions and taxes, 2026
| Item | Employer | Employee | Applies to |
|---|---|---|---|
| INPS pension (IVS) | 23.81% | 9.19% | All pay; up to €122,295 a year for employees first insured from 1996 |
| Additional pension contribution | — | 1% | Pay above €56,224 a year |
| Unemployment insurance (NASpI) | 1.31% | — | Plus 1.4% on fixed-term contracts |
| Other INPS contributions | Sector rates | Some funds | Family allowances, maternity, sickness and wage guarantee funds |
| INPS in total | About 30% | From 9.19% | Depends on sector, headcount and job category |
| INAIL accident insurance | Risk tariff | — | Rate set by INAIL for the activity |
| TFR severance | 7.41% | — | Annual pay divided by 13.5 |
| IRPEF income tax | — | 23% to 43% | Plus regional and municipal surtaxes |
| Withholdings and contributions | By the 16th | — | Of the following month, with the F24 form |
IRPEF rates and payroll tax measures for 2026
| Item | Rate | Applies to |
|---|---|---|
| IRPEF, first bracket | 23% | Income up to €28,000 |
| IRPEF, second bracket | 33% | €28,000 to €50,000 (35% until 2025) |
| IRPEF, third bracket | 43% | Income above €50,000 |
| Pay rises from renewed collective agreements | 5% flat tax | Employees with 2025 employment income up to €33,000 |
| Night, holiday and shift allowances | 15% flat tax | Up to €1,500, for employees with 2025 income up to €40,000 |
| Productivity bonuses | 1% flat tax | Up to €5,000 a year, in 2026 and 2027 |
| Electronic meal vouchers | Tax free | Up to €10 a day |
Italian payroll calendar
| When | What |
|---|---|
| Every month | Payslips and the UniEmens declaration to INPS |
| By the 16th of the following month | IRPEF withholdings and INPS contributions paid with the F24 form |
| Within 60 days of a first hire | The employee’s TFR choice, or automatic pension enrolment from 1 July 2026 |
| 16 March | Certificazione Unica to employees and to the Revenue Agency |
| 31 October | Form 770 withholding agent return |
| 31 December | TFR revaluation: 1.5% plus 75% of ISTAT inflation |
| December | 13th month salary under most collective agreements |
The cost example assumes an office employee at a services company paid 13 monthly salaries, with employer INPS contributions of about 30%. The exact INPS rate depends on the sector, headcount and job category, and INAIL premiums on the risk tariff. These are TopSource calculations from the verified rates.
Rates, thresholds and dates shown were verified on 12 October 2026 against the 2026 Budget Law (Law 199 of 30 December 2025), INPS circulars on contribution rates and on 2026 thresholds (circular 6 of 30 January 2026), the Civil Code, Law 92 of 2012, Legislative Decrees 66 of 2003 and 151 of 2001 and the rules on withholding agent returns and tax payments. This page is general information, not tax or legal advice.
How our Italian payroll service works
Why Choose TopSource for Global Payroll in Italy
TopSource for payroll, Employer of Record or any other of our services represents a simpler, more reliable and transparent option. If you would rather not employ staff in Italy directly, our Employer of Record in Italy can employ them on your behalf.
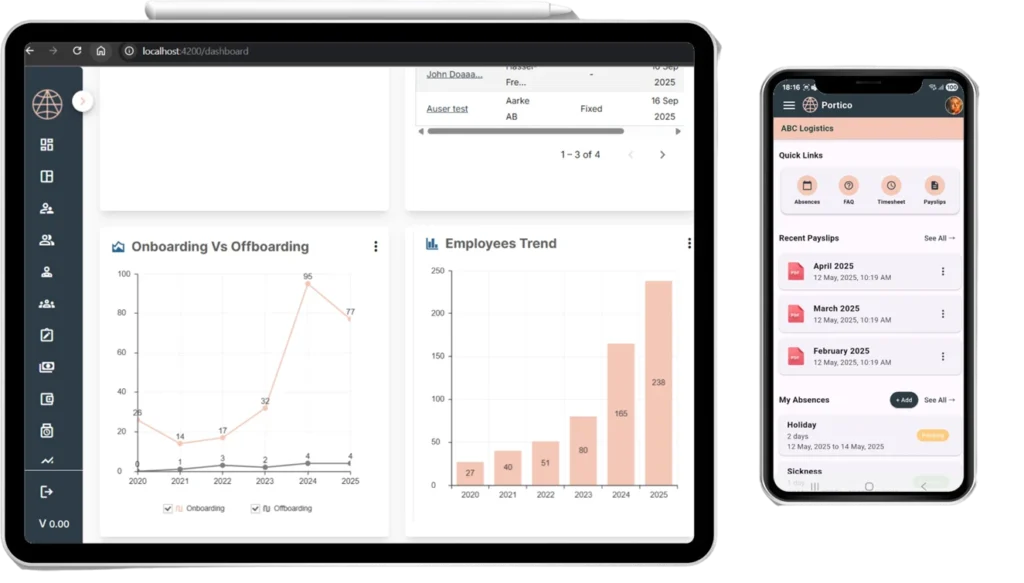
We don’t hide fees or sneak price increases. We run Italian payroll in-house and file under your own INPS, INAIL and withholding agent registrations rather than a bureau’s, so the same team that pays your F24 answers your calls. You get a named account manager, one consolidated monthly invoice covering salaries, contributions and fees, and one live Portico view of Italy beside every other country we run for you. Portico syncs with your time-tracking, leave and HR systems via API – set up by our onboarding team, not left to yours. GDPR, SOC 2 and ISO 27001 certified.
Other services
Accelerating your growth in Italy and beyond
TopSource goes far beyond payroll, acting as your end-to-end partner in global workforce management. From Employer of Record (EOR) services and seamless entity setup to localized accountancy and fractional HR support, we cover every aspect of international employment.
Meet our experts for Italy
Whether you’re entering the market or scaling operations, our specialists provide the insight and guidance you need to succeed in one of the world’s most dynamic and regulated employment landscapes. With TopSource, you’re backed by real experts, every step of the way.
Beyond a payroll serviceA globalization accelerator
Payroll platform
Global payroll simplified
Your intuitive hub for paying global teams. Simple, powerful, and designed to scale with you — no complexity, just clarity.
Audit
Eliminate barriers to growth
Avoid compliance issues across your global workforce and uncover opportunities to improve profitability. On a quarterly basis we’ll help you audit your global talent strategy to ensure it aligns with your business goals.
Intelligence
Build a data-driven talent strategy
Grow confidently and profitably with access to the latest TopSource insights & data on hiring markets, salary benchmarking & benefits.
Advisory
Expert guidance that turns complexity into clarity.
Whether you’re managing a global acquisition or entering a new market, you get clear guidance to navigate complex decisions, avoid delays, and accelerate your global expansion.
Italy payroll FAQs
Employers pay about 30% of gross pay to INPS, depending on sector and size, of which 23.81% is the pension contribution. On top come INAIL accident insurance at the employer’s risk tariff and TFR severance of one 13.5th of annual pay, about 7.41%.
The employer deducts IRPEF from each salary as withholding agent, at 23% up to €28,000, 33% from €28,000 to €50,000 and 43% above, after tax credits, plus regional and municipal surtaxes, and pays it with the F24 form by the 16th of the following month.
The 2026 Budget Law cut the middle IRPEF rate from 35% to 33% and added flat taxes of 5% on pay rises from renewed collective agreements, 15% on night, holiday and shift allowances and 1% on productivity bonuses, each with income limits. From 1 July 2026, first-time employees join a pension fund automatically.
TFR is the severance every Italian employee accrues: each year, annual pay divided by 13.5, revalued every 31 December by 1.5% plus 75% of inflation. It is paid when employment ends, for any reason, unless the employee sends it to a pension fund.
No. From 1 July 2026 it applies to private-sector employees hired for the first time: they join their collective agreement’s pension fund with their full TFR unless they opt out within 60 days. For other new hires, the employer records the choice they made before and explains their options.
An office employee on €3,000 a month, paid 13 times a year, costs about €53,589 a year: €39,000 of salary, about €11,700 of INPS and €2,888.89 of TFR, some 37% on top of salary before INAIL. Tell us the role, collective agreement and salary and we’ll send the full cost within one business day.
There is no statutory minimum wage. Minimum pay for each job level is set by the national collective agreement (CCNL) that applies to the employer, along with the 13th month and, in some sectors, a 14th.
Normal working time is 40 hours a week, and average hours including overtime cannot exceed 48 a week over four months. Without a collective agreement, overtime needs the employee’s consent and is capped at 250 hours a year; most agreements set their own rules.
Five months, normally two before the expected birth and three after, paid at 80%. Fathers take ten working days at full pay, and each parent can then take parental leave until the child turns 14, partly paid.
Running Italian payroll means registering with INPS and INAIL and acting as withholding agent, which in practice is done through an Italian company or branch. TopSource can run payroll for your Italian entity or employ your team through our Employer of Record service.
Looking at other markets too?
We help organizations employ and pay teams in 164 countries.