Payroll Services in Cyprus
Fully managed Cypriot payroll – social insurance up to the 2026 ceiling, GHS contributions, PAYE under the new 2026 tax bands and the monthly declarations in Tax For All, with a named specialist a phone call away.

TopSource rated 5/5 by our customers
What Cypriot payroll actually involves
Cypriot payroll combines social insurance with three employer-only funds, contributions to the General Healthcare System (GHS, or GeSY) and income tax withheld under PAYE. The 2026 tax reform raised the tax-free threshold and moved every band, and monthly payroll declarations now go through the Tax For All portal.
Our Partners Globally




“Their expertise and understanding of the unique hiring, payment, and human resource practices in each country has been nothing short of outstanding. Our Client Success Manager, has done just that … ensured our success. Her availability and willingness to engage on a personal level has made all the difference.”
“Excellent service, especially from our account manager who has gone above and beyond to help us use the platform effectively. Our manager, significantly simplifies my workload. It is like having your own TopSource HR representative on your team.”
“TopSource has been our go-to resource for international hiring. They are responsive, thorough, respectful and knowledgeable. The Client Success team has provided us with the utmost customer service, and the more we use TopSource, the more, it gives us access to more resources and knowledge.”
Employer Costs in Cyprus Explained
A Cypriot employee costs about 15.4% on top of salary at €3,000 a month, and the share falls as salaries rise because social insurance and two of the employer funds stop at €5,742 a month. Above that ceiling only the 2% Social Cohesion Fund and the 2.9% GHS contribution keep growing, and GHS stops at €180,000 a year. Income tax is withheld from the employee’s pay. Here’s the breakdown.
Employers and employees each pay 8.8% social insurance on earnings up to the 2026 ceiling of €1,325 a week, €5,742 a month or €68,904 a year. The rate rises to 9.3% each from 1 January 2029 and keeps rising every five years after that. Employers also pay 1.2% to the Redundancy Fund and 0.5% to the Human Resource Development fund on the same capped earnings, and 2% to the Social Cohesion Fund on all earnings without a ceiling.
Employers without an exemption also pay into the Central Holiday Fund, which then pays employees’ annual leave. Most employers obtain the exemption and pay annual leave directly. Contributions are paid to the Social Insurance Services by the end of the month following the month of pay.
The General Healthcare System (GHS, known locally as GeSY) is funded by contributions of 2.9% from employers and 2.65% from employees on emoluments up to €180,000 a year. The employer deducts the employee’s share with income tax and pays both through the monthly payroll declaration in the Tax For All portal, by the end of the following month.
GHS applies to bonuses and to a 13th salary where one is paid. A 13th salary is not required by law in Cyprus; it is paid only where a collective agreement or the employment contract provides for it.
The tax reform passed by Parliament on 22 December 2025 and in force from 1 January 2026 raised the tax-free threshold to €22,000. Income from €22,001 to €32,000 is taxed at 20%, €32,001 to €42,000 at 25%, €42,001 to €72,000 at 30% and anything above €72,000 at 35%. In 2025 the threshold was €19,500 and the 35% rate started above €60,000.
Employee social insurance, GHS and provident fund contributions are deductible up to a fifth of chargeable income, and new family deductions of €1,000 for the first child, €1,250 for the second and €1,500 for each further child apply within family income limits. The employer withholds tax under PAYE each month and pays it with the monthly payroll declaration by the end of the following month.
For an employee on €3,000 a month, the employer pays €264 of social insurance, €51 to the Redundancy Fund and training fund, €60 to the Social Cohesion Fund and €87 of GHS: €3,462 a month, 15.4% on top of salary. At €8,000 a month the capped contributions stop at €5,742 and the total is €8,994.91, 12.4% on top. At €16,000 a month GHS also stops, at €15,000 a month, and the employer cost falls to 8.5%.
The national minimum wage is €1,088 a month from 1 January 2026, or €979 during the first six months with the same employer, and applies pro rata to part-time staff. Some groups, such as domestic workers and seafarers, are outside the national minimum wage.
Working time is limited to 48 hours a week on average, including overtime. Employees are entitled to at least 20 working days of paid annual leave on a five-day week, or 24 on a six-day week. Sick pay comes from Social Insurance from the fourth day of illness rather than from the employer. Social Insurance also pays maternity allowance for 22 weeks and paternity allowance for 2 weeks, and each parent can take up to 18 weeks of parental leave per child.
After 26 weeks of service, an employer must give notice of one week, rising to eight weeks after six years. Redundancy payments for employees with at least 104 weeks of service come from the state Redundancy Fund, financed by the employer’s 1.2% contribution, while compensation for unfair dismissal is paid by the employer.
Cypriot employer contributions and payroll costs, 2026
| Contribution | Employer | Employee | Applies to |
|---|---|---|---|
| Social insurance | 8.8% | 8.8% | Earnings up to €5,742 a month; 9.3% from 2029 |
| Redundancy Fund | 1.2% | — | Earnings up to €5,742 a month |
| Human Resource Development (training) | 0.5% | — | Earnings up to €5,742 a month |
| Social Cohesion Fund | 2% | — | All earnings, no ceiling |
| General Healthcare System (GHS) | 2.9% | 2.65% | Earnings up to €180,000 a year |
| Central Holiday Fund | Set by the fund | — | Only employers without an exemption |
| Income tax (PAYE) | — | 0% to 35% | Withheld monthly; €22,000 tax-free |
Cypriot income tax bands, 2025 and 2026
| Rate | 2025 taxable income | 2026 taxable income |
|---|---|---|
| 0% | Up to €19,500 | Up to €22,000 |
| 20% | €19,501 to €28,000 | €22,001 to €32,000 |
| 25% | €28,001 to €36,300 | €32,001 to €42,000 |
| 30% | €36,301 to €60,000 | €42,001 to €72,000 |
| 35% | Above €60,000 | Above €72,000 |
Employer cost of monthly salaries in Cyprus, 2026
| Monthly salary | Social insurance 8.8% | Redundancy and training 1.7% | Social Cohesion 2% | GHS 2.9% | Total monthly cost | On top of salary |
|---|---|---|---|---|---|---|
| €3,000 | €264 | €51 | €60 | €87 | €3,462 | 15.4% |
| €8,000 | €505.30 | €97.61 | €160 | €232 | €8,994.91 | 12.4% |
| €16,000 | €505.30 | €97.61 | €320 | €435 | €17,357.91 | 8.5% |
Social insurance, Redundancy Fund and training contributions are capped at €5,742 a month, and GHS at €15,000 a month (€180,000 a year). These are TopSource calculations from the verified 2026 rates.
Rates, ceilings and amounts shown are for 2026 and were verified on 1 October 2026 against the Social Insurance Services ceiling announcement, the 2026 tax reform, the 2026 minimum wage decree and published tax sources. This page is general information, not tax or legal advice.
How our Cypriot payroll service works
Why Outsource Your Cyprus Payroll to TopSource
TopSource for payroll, Employer of Record or any other of our services represents a simpler, more reliable and transparent option.
We don’t hide fees or sneak price increases. We run Cypriot payroll in-house and file under your own Social Insurance and tax registrations rather than a bureau’s, so the same team that files your monthly declarations answers your calls. You get a named account manager, one consolidated monthly invoice covering salaries, contributions, taxes and fees, and one live Portico view of Cyprus beside every other country we run for you. Portico syncs with your time-tracking, leave and HR systems via API – set up by our onboarding team, not left to yours. GDPR, SOC 2 and ISO 27001 certified.
Other services
Accelerating your growth in Cyprus and beyond
TopSource goes far beyond payroll, acting as your end-to-end partner in global workforce management. From Employer of Record (EOR) services and seamless entity setup to localized accountancy and fractional HR support, we cover every aspect of international employment.
Meet our experts for Cyprus
Whether you’re entering the market or scaling operations, our specialists provide the insight and guidance you need to succeed in one of the world’s most dynamic and regulated employment landscapes. With TopSource, you’re backed by real experts, every step of the way.
Beyond a payroll serviceA globalization accelerator
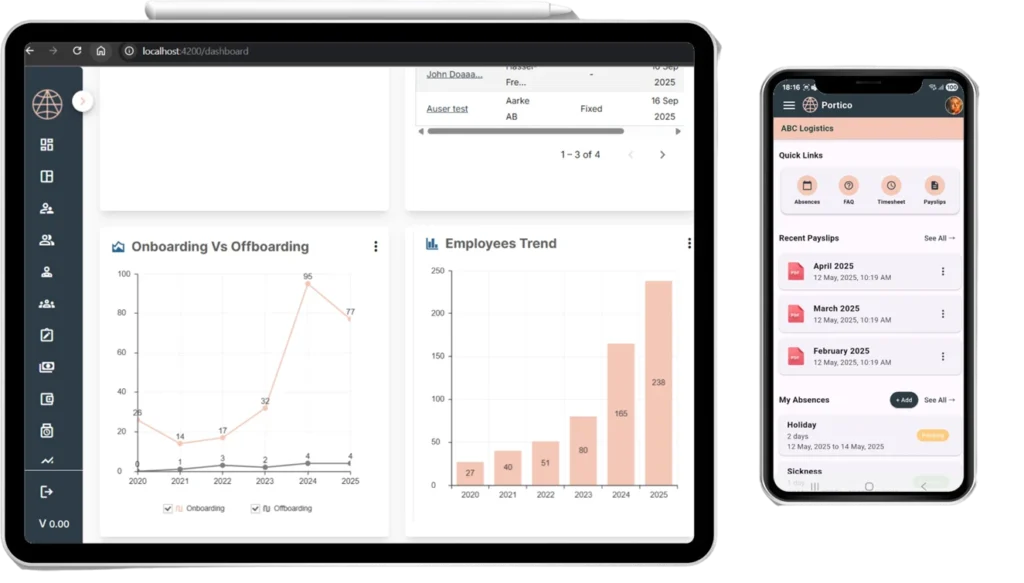
Payroll platform
Global payroll simplified
Your intuitive hub for paying global teams. Simple, powerful, and designed to scale with you — no complexity, just clarity.
Audit
Eliminate barriers to growth
Avoid compliance issues across your global workforce and uncover opportunities to improve profitability. On a quarterly basis we’ll help you audit your global talent strategy to ensure it aligns with your business goals.
Intelligence
Build a data-driven talent strategy
Grow confidently and profitably with access to the latest TopSource insights & data on hiring markets, salary benchmarking & benefits.
Advisory
Expert guidance that turns complexity into clarity.
Whether you’re managing a global acquisition or entering a new market, you get clear guidance to navigate complex decisions, avoid delays, and accelerate your global expansion.
Cypriot payroll FAQs
Employers pay 8.8% social insurance, 1.2% to the Redundancy Fund and 0.5% for training on earnings up to €5,742 a month, 2% to the Social Cohesion Fund on all earnings and 2.9% GHS on earnings up to €180,000 a year. Employees pay 8.8% social insurance and 2.65% GHS.
The maximum insurable earnings for 2026 are €1,325 a week, €5,742 a month or €68,904 a year. Social insurance, Redundancy Fund and training contributions stop at the ceiling, while the Social Cohesion Fund applies to all earnings.
Income up to €22,000 is tax-free. Income from €22,001 to €32,000 is taxed at 20%, €32,001 to €42,000 at 25%, €42,001 to €72,000 at 30% and anything above €72,000 at 35%.
From 1 January 2026 the tax-free threshold rose from €19,500 to €22,000 and every band was widened, with 35% now starting above €72,000 instead of €60,000. New deductions apply for children, primary residence rent or mortgage interest and energy-saving spending, within family income limits.
Employers pay 2.9% and employees 2.65% of emoluments to the General Healthcare System, on income up to €180,000 a year. The employer withholds the employee’s share and pays both through the monthly payroll declaration.
The national minimum wage is €1,088 a month from 1 January 2026 for full-time employees with six months of service with the same employer, and €979 before that. It applies pro rata to part-time staff.
PAYE and GHS withheld from salaries are declared and paid through the Tax For All portal by the end of the following month. Social insurance and the employer funds are paid to the Social Insurance Services by the end of the month following the month of pay.
No. Cypriot law does not require a 13th salary. It is paid only where a collective agreement or the employment contract provides for it, and when it is paid it carries social insurance, GHS and income tax like other pay.
Employees are entitled to at least 20 working days of paid annual leave on a five-day week, or 24 days on a six-day week. Public holidays, maternity leave and sick leave do not count as annual leave.
Registering as an employer with the Social Insurance Services requires a local entity, such as a Cypriot company or a registered branch. Without one, the usual route is an Employer of Record. TopSource can run payroll for your Cypriot entity or employ your team through our Employer of Record service.
Looking at other markets too?
We help organizations employ and pay teams in 164 countries.