Payroll Services in Bulgaria
Fully managed Bulgarian payroll in euro – Declarations 1 and 6 filed to the revenue agency by the 25th with contributions and withheld tax paid the same day, the correct insurance ceiling applied for each period of a split year, minimum insurance thresholds mapped to the new KID-2025 classifier, and every contract registered within three days, with a named specialist a phone call away.

TopSource rated 5/5 by our customers
What Bulgarian payroll actually involves
Bulgaria is one of the least expensive places in the European Union to employ someone, and 2026 was the year almost everything about how you calculate it changed. The country adopted the euro on 1 January, so every figure – the minimum wage, the contribution ceiling, the insurance thresholds, even the Labour Code fines – is now denominated in euro at a fixed rate that produces deliberately un-round numbers. Then the social insurance budget arrived seven months late, which means a 2026 payroll runs on one set of parameters to 31 July and another from 1 August. Underneath that sit two features foreign employers consistently miss: a floor system that can force contributions above actual pay, and a mandatory supplement of at least 0.6% of salary for every year of an employee’s relevant experience.
Our Partners Globally




Calculate Your Employee Costs in Bulgaria
Enter a gross annual salary to see the full employer cost of a Bulgarian employee – social security at 18.92% of insurable income, capped at the maximum insurable income of €2,300 a month, or €27,600 a year. Because the ceiling applies, the employer contribution stops growing at €5,221.92 whatever the salary, which is why the effective rate falls as pay rises. The figure uses the minimum 0.40% occupational accident rate; a higher-risk activity adds up to 0.70 points. It excludes the mandatory length-of-service supplement, which the tables below explain.
Employment Cost Calculator
*Indicative figures only and not definitive legal advice. Local regulations change frequently. Consult an expertBulgaria
| British Pound | Bulgaria | |
|---|---|---|
| Base Salary (per month) | ||
| Employer Contributions | ||
| Total Cost (Annual) | ||
| Total Cost (Monthly) |
“Their expertise and understanding of the unique hiring, payment, and human resource practices in each country has been nothing short of outstanding. Our Client Success Manager, has done just that … ensured our success. Her availability and willingness to engage on a personal level has made all the difference.”
“Excellent service, especially from our account manager who has gone above and beyond to help us use the platform effectively. Our manager, significantly simplifies my workload. It is like having your own TopSource HR representative on your team.”
“TopSource has been our go-to resource for international hiring. They are responsive, thorough, respectful and knowledgeable. The Client Success team has provided us with the utmost customer service, and the more we use TopSource, the more, it gives us access to more resources and knowledge.”
Employer Costs in Bulgaria Explained
Employer social security in Bulgaria is 18.92% to 19.62% of insurable income in 2026, and the employee pays 13.78%, with a flat 10% income tax on top of that. Because insurable income is capped – at €2,111.64 a month to 31 July 2026 and €2,300 from 1 August – the effective employer rate falls above the ceiling: 18.92% at €1,500 a month, about 12.4% at €3,500 and about 7.3% at €6,000. That makes Bulgaria one of the cheapest EU jurisdictions for a senior professional. Two things sit outside those percentages and both add real cost: the mandatory length-of-service supplement of at least 0.6% of basic salary per year of relevant experience, and the minimum insurance thresholds, which can require contributions on a base higher than the employee’s actual pay. Here’s the breakdown.
Bulgaria joined the euro area on 1 January 2026, the twenty-first member to do so. The Council of the European Union adopted the final legal acts on 8 July 2025, and the national implementing law – the Law on the Introduction of the Euro in the Republic of Bulgaria, published in State Gazette No. 65 of 8 August 2025 – set the mechanics. The conversion rate is irrevocably fixed at 1 EUR = 1.95583 BGN and must be used at all five decimal places, never rounded or truncated. Dual circulation ran for one month, from 1 to 31 January 2026, and was not extended.
For payroll the practical consequences were mechanical rather than legal. Lev amounts in statutes and contracts redenominate arithmetically at the fixed rate, rounded to the cent, and the euro law contains no provision re-basing figures to round euro numbers – which is why Bulgarian payroll figures now look odd in euro. The minimum wage is €620.20, not a round number, because it was set as BGN 1,213. Labour Code fines are the same: the general employer penalty band is €766.94 to €7,669.38, because it was BGN 1,500 to BGN 15,000.
One useful indicator of how complete the transition is: the National Social Security Institute now publishes its parameters in euro only, with no lev equivalents. Any payroll system, contract template or budget model still expressing Bulgarian figures in leva is working from pre-2026 data.
For an employee born on or after 1 January 1960 – the normal case – total social security is 32.70% to 33.40% of insurable income, split roughly 19% employer and 13.78% employee. The employer’s share comprises 8.22% to the state pension fund, 2.80% to the mandatory second-pillar universal pension fund, 2.10% for general sickness and maternity, 0.60% for unemployment, 4.80% for health insurance, and 0.40% to 1.10% for occupational accident and disease, which is employer-only and differentiated by economic activity. The employee pays 6.58%, 2.20%, 1.40%, 0.40% and 3.20% respectively. For an employee born before 1960 there is no second pillar and the whole 19.80% pension element goes to the state fund – the employer and employee totals are identical, only the allocation differs. Teaching posts carry a further 4.30% teachers’ pension fund contribution, entirely at the employer’s expense.
The base is capped, and in 2026 the cap moved mid-year. From 1 January to 31 July the maximum monthly insurable income was €2,111.64; from 1 August it is €2,300. Because the ceiling applies to both sides, the effective employer rate falls above it: 18.92% at €1,500 a month, about 12.4% at €3,500, about 7.3% at €6,000.
Underneath the ceiling sits a floor system that catches foreign employers out. The minimum insurance thresholds – minimalni osiguritelni dohodi, or MOD – set a minimum insurable income for each combination of economic activity and occupational group, published as an annex to the annual social insurance budget act. They were not abolished, contrary to a common belief; they were restructured. From 1 August 2026 they are mapped onto the new KID-2025 economic activity classifier, replacing KID-2008, which is a real payroll configuration change rather than a paper one. Indicative floors from August 2026 run from about €716 a month for administrative support staff to about €936 for managers. If an employee’s actual pay is below the MOD for their activity and occupation, contributions are still calculated on the MOD.
From 1 August 2026 there is also a new obligation for a specific population: state civil servants, judges, prosecutors, investigators and judicial staff, previously insured wholly at the employer’s expense, now make employee-side contributions on transitional splits, moving to the standard distribution on 1 January 2027.
Bulgaria applies a flat personal income tax of 10% on employment income, with no bands and no allowance. The base is gross pay less the employee’s own mandatory social security and health contributions, so the effective rate on gross is lower than 10%. Tax is withheld monthly and reconciled annually.
The arithmetic is unusually clean, and worth stating on the page because it is a genuine selling point of the jurisdiction. An employee earning up to the insurance ceiling takes home 77.6% of gross, whatever the salary – because both the 13.78% contribution and the 10% tax are proportional within the cap. Above the ceiling, net rises: at €6,000 a month gross the employee keeps about 85% of it, because contributions have stopped and only the flat tax continues.
A small number of reliefs are administered through or around payroll, principally the child tax relief and disability relief, which are claimed annually rather than applied monthly by default. Food vouchers up to €102.26 a month are non-taxable and outside the contribution base, which is why they are close to universal in Bulgarian remuneration packages.
The minimum wage from 1 January 2026 is €620.20 a month, or €3.74 an hour, set by Council of Ministers Decree No. 243 of 13 November 2025 and published in State Gazette No. 98 of 18 November 2025 – a 12.6% increase. Since 2024 the mechanism has been statutory rather than discretionary: Article 244 of the Labour Code requires the minimum wage to be set by 1 September each year at 50% of the average gross wage over a defined four-quarter reference period, implementing the EU adequate minimum wages directive. There are twelve monthly payments; a thirteenth salary is neither mandatory nor a general custom in Bulgaria.
The working week is 40 hours over five days, with an eight-hour day. Overtime is capped at 150 hours a year – a figure only a collective agreement can raise, to 300 hours, and which employee consent cannot raise at all – with monthly, weekly and two-day sub-limits. Premiums are at least 50% on an ordinary working day, 75% on a weekly rest day and 100% on an official public holiday. The night period is 22:00 to 06:00 and night hours are reduced, with seven hours counting as a full day. Employers must keep a register of overtime and report it to the Labour Inspectorate. Where a post is designated as open-ended working time, overtime premiums do not apply and the compensation is instead at least five additional days of paid annual leave.
Paid annual leave is a minimum of 20 working days, with five more for hazardous conditions or open-ended working time, and 26 days for employees with at least 50% reduced capacity. Sick pay is the item foreign employers most often get wrong: the employer pays the first two working days at 70% of average daily gross remuneration – reduced from three days with effect from 1 January 2024 – and the National Social Security Institute takes over from the third day at 80% of average daily insurable income. For a work accident or occupational disease there are no employer-paid days and the rate is 90% from day one. Sick notes are now issued fully electronically and transmitted automatically to both the institute and the employer.
Maternity leave is 410 calendar days, of which 45 fall before the expected date, paid at 90% of average gross daily income over the preceding 24 months and requiring 12 months of insurance for sickness and maternity. After it, a flat childcare benefit runs to the child’s second birthday. Fathers receive 15 calendar days at the birth, and – since the 2022 transposition of the EU work-life balance directive – a further two months of non-transferable leave usable until the child turns eight. Since 1 July 2025, cash benefits are not payable to anyone who actually performs work during the leave period.
Two monthly returns carry Bulgarian payroll. Declaration 1 reports per-person data – insurable income, contribution bases, days insured, contributions by fund and income tax withheld. Declaration 6 reports the aggregate amounts the employer owes. Both are filed electronically to the National Revenue Agency by the 25th of the following month, and the contributions and withheld tax are paid on the same date. The annual Declaration 6 for income tax is due by 25 February. The governing instrument is Ordinance No. H-13 of 17 December 2019.
Employment records changed in 2025. The paper labour book, the trudova knizhka, was replaced by the unified electronic employment record held in the Employment Register maintained by the revenue agency, from 1 June 2025 for the private sector and 1 June 2026 for civil servants. Employers had until 1 June 2026 to close out existing paper books, record each employee’s history to 31 May 2025 and return the completed book to the employee – that deadline has now passed, and closed books remain the official record for pre-transition service. Going forward, conclusion and amendment of a contract must be filed within three days, termination within seven, and a change of employer within ten. The data set is wider than the old book: it captures the start of performance, working time duration, leave used, recognised length of service and the date of any severance payment.
A Bulgarian entity is not always required. A foreign employer with no physical presence in Bulgaria – for example where employees work remotely from home – can register directly with the revenue agency for a service number under the Tax and Social Insurance Procedure Code, and with the social security institute as an insurer. That route needs apostilled and translated corporate and tax documents. Where the employer keeps an office or production facility, holds client meetings or otherwise conducts business in Bulgaria, a branch or subsidiary is required, and a fixed place of business may also create a permanent establishment for corporate tax. A local bank account is advisable either way, because payment processing failures are the common practical problem.
On termination, notice is set by contract subject to statutory minimums, and the Labour Code provides defined grounds together with compensation entitlements – on redundancy, on retirement, and for accrued unused leave. Certain categories require the prior consent of the Labour Inspectorate before dismissal. Labour Code penalties are substantial relative to Bulgarian salaries: the general employer breach band is €766.94 to €7,669.38, with €511.29 to €5,112.92 for the responsible official, and failure to close out a paper labour book within the transition period carries the same range as a general breach.
Bulgarian contribution rates, 2026
| Contribution | Employer | Employee | Applies to |
|---|---|---|---|
| Pension – state social insurance (DOO) | 8.22% | 6.58% | 14.80% total. For employees born before 1960 the pension element is 19.80% with no second pillar |
| Universal Pension Fund (second pillar) | 2.80% | 2.20% | 5.00% total. Mandatory for employees born on or after 1 January 1960 |
| General sickness and maternity | 2.10% | 1.40% | 3.50% total, split 60:40 |
| Unemployment | 0.60% | 0.40% | 1.00% total, split 60:40 |
| Occupational accident and disease (TZPB) | 0.40% – 1.10% | — | Employer only, differentiated by economic activity. Annex to the social insurance budget act |
| Health insurance (NHIF) | 4.80% | 3.20% | 8.00% total, split 60:40 |
| Guaranteed Workers’ Claims Fund | 0.00% | — | Set at nil for 2026 |
| Total social security | 18.92% – 19.62% | 13.78% | 32.70% – 33.40% combined, on insurable income up to the ceiling |
| Teachers’ pension fund | 4.30% | — | Additional, employer only, for staff in teaching posts |
| Personal income tax | — | 10% flat | On gross less the employee’s own contributions. No bands, no allowance |
| Length-of-service supplement | At least 0.6% per year of service | — | Mandatory addition to basic salary, recalculated annually. Ordinance on the Structure and Organisation of Wages, art. 12 |
| Minimum wage | €620.20 a month | — | €3.74 an hour. Decree No. 243 of 13 November 2025, from 1 January 2026 (+12.6%) |
Bulgarian thresholds and the 2026 split year
| Item | 2026 figure | Notes |
|---|---|---|
| Currency | Euro, since 1 January 2026 | Irrevocable rate 1 EUR = 1.95583 BGN, used at five decimals. Dual circulation ended 31 January 2026. Law published in State Gazette No. 65 of 8 August 2025 |
| Maximum insurable income, 1 Jan – 31 Jul 2026 | €2,111.64 a month | Frozen at the 2025 level by the extension law, State Gazette No. 113 of 23 December 2025 |
| Maximum insurable income, 1 Aug – 31 Dec 2026 | €2,300.00 a month | Social insurance budget act, State Gazette No. 68 of 28 July 2026, effective 1 August 2026 |
| Minimum insurable income – employees | The MOD for their activity and occupation, never below €620.20 | Minimum insurance thresholds by economic activity and occupational group. Not abolished – restructured |
| MOD classifier | Re-mapped to KID-2025 from 1 August 2026 | Replaces KID-2008. A payroll configuration action, not a paper change |
| Indicative MOD floors from 1 August 2026 | €716 to €936 a month | Administrative support staff up to managers. Technicians about €771, specialists about €826 |
| Non-taxable food vouchers | €102.26 a month | Outside both the tax base and the contribution base |
| Health contribution during unpaid leave | €24.81 a month | 8% on half the minimum insurable income, from 1 August 2026 |
| Net pay as a share of gross | 77.6% up to the ceiling; about 85% at €6,000 | Because both the 13.78% contribution and the 10% tax are proportional within the cap |
| Employer effective rate | 18.92% to the ceiling, then falling | About 12.4% at €3,500 a month and 7.3% at €6,000 |
Gross to net and employer cost, monthly
| Monthly gross | Insurable base | Employer cost | Effective rate | Employee contributions | Income tax at 10% | Net pay |
|---|---|---|---|---|---|---|
| €620.20 (minimum wage) | €620.20 | €117.34 | 18.92% | €85.46 | €53.47 | €481.26 |
| €1,000 | €1,000.00 | €189.20 | 18.92% | €137.80 | €86.22 | €775.98 |
| €1,500 | €1,500.00 | €283.80 | 18.92% | €206.70 | €129.33 | €1,163.97 |
| €2,300 (at the August ceiling) | €2,300.00 | €435.16 | 18.92% | €316.94 | €198.31 | €1,784.75 |
| €3,500 | €2,300.00 | €435.16 | 12.43% | €316.94 | €318.31 | €2,864.75 |
| €6,000 | €2,300.00 | €435.16 | 7.25% | €316.94 | €568.31 | €5,114.75 |
Annual employer cost, and where the ceiling bites
| Monthly gross | Annual gross | Annual employer contributions | Total annual cost | Effective rate | Note |
|---|---|---|---|---|---|
| €1,500 | €18,000 | €3,405.60 | €21,405.60 | 18.92% | Below the ceiling – the full rate applies |
| €2,300 | €27,600 | €5,221.92 | €32,821.92 | 18.92% | Exactly at the August 2026 ceiling |
| €3,500 | €42,000 | €5,221.92 | €47,221.92 | 12.43% | Contributions have stopped rising |
| €6,000 | €72,000 | €5,221.92 | €77,221.92 | 7.25% | The employer’s contribution is unchanged from €2,300 |
| €10,000 | €120,000 | €5,221.92 | €125,221.92 | 4.35% | Among the lowest senior employment costs in the EU |
The tables use the employer minimum of 18.92%, being the 0.40% occupational accident rate – a higher-risk activity adds up to 0.70 points – and the maximum insurable income of €2,300 in force from 1 August 2026. They exclude the mandatory length-of-service supplement, which adds at least 0.6% of basic salary per year of relevant experience and is the largest omission, and they exclude food vouchers. Because the ceiling changed on 1 August 2026, a full-year 2026 calculation is seven months at the €2,111.64 ceiling and five at €2,300 – a base of €26,281.48 and an annual employer maximum of €4,972.46 rather than €5,221.92. The tables use the August figure throughout for clarity; use the blended number for an actual 2026 accrual. The occupational accident rate is set by economic activity in an annex to the annual social insurance budget act, so it can move without any change in your own claims experience – three activities moved on 1 August 2026. The minimum insurance thresholds are set in the same annex by activity and occupational group, and were re-mapped onto the KID-2025 classifier from that date. These are TopSource calculations from the verified 2026 rates, not published figures.
Rates, ceilings and thresholds shown are for the 2026 calendar year and were verified on 9 September 2026. All amounts are in euro, following Bulgaria’s adoption of the euro on 1 January 2026 at the fixed rate of 1 EUR = 1.95583 BGN. Note that the maximum insurable income changed on 1 August 2026, so figures for January to July 2026 differ. This page is general information, not tax or legal advice.
How our Bulgarian payroll service works
Why TopSource for Bulgarian Payroll
TopSource for payroll, Employer of Record or any other of our services represents a simpler, more reliable and transparent option.
We don’t hide fees or sneak price increases. We run Bulgarian payroll in-house, not brokered to a local accounting office – the same team that files your Declarations 1 and 6 answers your calls, in English and Bulgarian. You get a named account manager, one consolidated monthly invoice covering salaries, contributions and fees, and one live Portico view of Bulgaria beside every other country we run for you. Portico syncs with your time-tracking, leave and HR systems via API – set up by our onboarding team, not left to yours. GDPR, SOC 2 and ISO 27001 certified.
Other services
Accelerating your growth in Bulgaria and beyond
TopSource goes far beyond payroll, acting as your end-to-end partner in global workforce management. From Employer of Record (EOR) services and seamless entity setup to localized accountancy and fractional HR support, we cover every aspect of international employment.
Meet our experts for Bulgaria
Whether you’re entering the market or scaling operations, our specialists provide the insight and guidance you need to succeed in one of the world’s most dynamic and regulated employment landscapes. With TopSource, you’re backed by real experts, every step of the way.
Beyond a payroll serviceA globalization accelerator
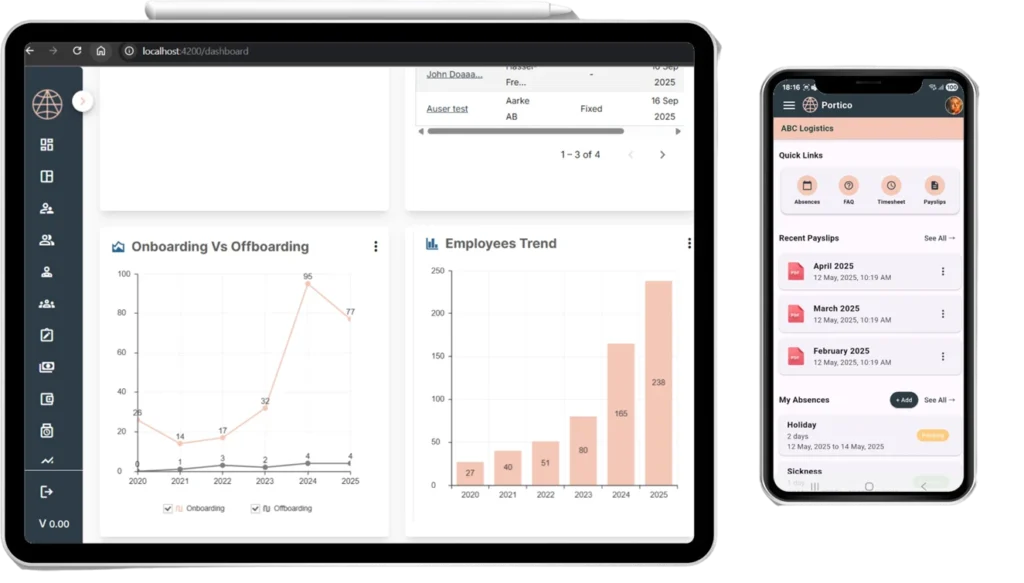
Payroll platform
Global payroll simplified
Your intuitive hub for paying global teams. Simple, powerful, and designed to scale with you — no complexity, just clarity.
Audit
Eliminate barriers to growth
Avoid compliance issues across your global workforce and uncover opportunities to improve profitability. On a quarterly basis we’ll help you audit your global talent strategy to ensure it aligns with your business goals.
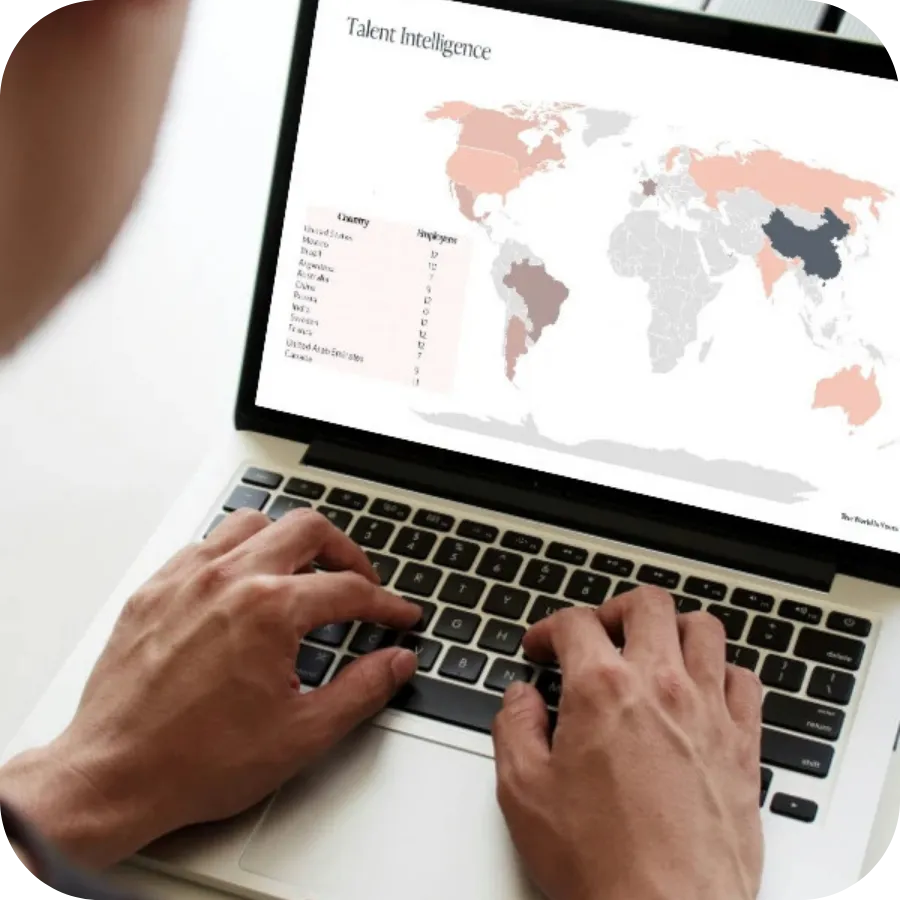
Intelligence
Build a data-driven talent strategy
Grow confidently and profitably with access to the latest TopSource insights & data on hiring markets, salary benchmarking & benefits.
Advisory
Expert guidance that turns complexity into clarity.
Whether you’re managing a global acquisition or entering a new market, you get clear guidance to navigate complex decisions, avoid delays, and accelerate your global expansion.
Bulgarian payroll FAQs
Yes. Bulgaria adopted the euro on 1 January 2026, becoming the twenty-first member of the euro area, at the irrevocably fixed rate of 1 EUR = 1.95583 BGN. The Council of the European Union adopted the final legal acts on 8 July 2025 and the national implementing law was published in State Gazette No. 65 of 8 August 2025. Dual circulation of the lev and the euro ran for one month, from 1 to 31 January 2026, and was not extended. All Bulgarian payroll figures are now denominated in euro.
Employer social security contributions in Bulgaria are 18.92% to 19.62% of insurable income in 2026, and the employee pays 13.78%. The employer’s share comprises 8.22% state pension, 2.80% universal pension fund, 2.10% sickness and maternity, 0.60% unemployment, 4.80% health insurance and 0.40% to 1.10% occupational accident cover, which varies by economic activity. Teaching posts carry an additional 4.30% teachers’ pension fund contribution at the employer’s expense.
The Bulgarian minimum wage is €620.20 a month, or €3.74 an hour, from 1 January 2026 – a 12.6% increase, set by Council of Ministers Decree No. 243 of 13 November 2025. Since 2024 the level has been determined by statute rather than negotiation: article 244 of the Labour Code requires it to be set at 50% of the average gross wage over a defined four-quarter reference period, implementing the EU directive on adequate minimum wages.
Yes, and in 2026 it changed mid-year. The maximum monthly insurable income was €2,111.64 from 1 January to 31 July 2026, frozen at the 2025 level by an extension law, and rose to €2,300 from 1 August 2026 when the social insurance budget act took effect. Because the ceiling applies to both employer and employee, the effective employer rate falls above it – from 18.92% at €1,500 a month to about 12.4% at €3,500 and 7.3% at €6,000.
Bulgaria applies a flat personal income tax of 10% on employment income, with no bands and no personal allowance. The base is gross pay less the employee’s own mandatory social security and health contributions, so the effective rate on gross is below 10%. An employee earning up to the insurance ceiling takes home 77.6% of gross whatever their salary; above the ceiling the net share rises, reaching about 85% at €6,000 a month.
Minimum insurance thresholds – minimalni osiguritelni dohodi, or MOD – set a minimum insurable income for each combination of economic activity and occupational group, published as an annex to the annual social insurance budget act. They still exist for 2026; they were restructured rather than abolished, and from 1 August 2026 are mapped onto the new KID-2025 activity classifier. Where an employee’s actual pay falls below the applicable threshold, contributions are calculated on the threshold instead.
The employer pays the first two working days of incapacity at 70% of the employee’s average daily gross remuneration, and the National Social Security Institute pays from the third day at 80% of average daily insurable income. The employer-paid period was reduced from three days to two with effect from 1 January 2024. For a work accident or occupational disease there are no employer-paid days at all and the rate is 90% from day one.
Bulgarian employees are entitled to an additional payment of at least 0.6% of their basic salary for each year of acquired service and professional experience in the same or a similar role, under article 12 of the Ordinance on the Structure and Organisation of Wages. It is mandatory, recalculated annually, and cannot be refused once the conditions are met. Qualifying service includes work in other EU member states, so an employee with fifteen years of relevant experience carries a supplement of at least 9%.
Bulgarian employees receive a minimum of 20 working days of paid annual leave, with five additional days for hazardous conditions or an open-ended working day, and 26 days for employees with at least 50% reduced working capacity. Maternity leave is 410 calendar days, of which 45 fall before the expected date, paid at 90% of average gross daily income. Fathers receive 15 calendar days at the birth plus a further two months of non-transferable leave usable until the child turns eight.
Not always. A foreign employer with no physical presence in Bulgaria – for example where employees work remotely from home – may register directly with the National Revenue Agency for a service number under the Tax and Social Insurance Procedure Code, and with the National Social Security Institute as an insurer, without incorporating. Where the employer maintains an office or production facility, holds client meetings or otherwise conducts business in Bulgaria, a branch or subsidiary is required and a fixed place of business may also create a permanent establishment for corporate tax.
Looking at other markets too?
We help organizations with employ and pay teams in over 180 countries.