Payroll Services in Papua New Guinea
Fully managed Papua New Guinea payroll: salary or wages tax withheld under the new Income Tax Act 2025, superannuation paid to your fund on time, and a named specialist a phone call away.

TopSource rated 5/5 by our customers
What payroll in Papua New Guinea actually involves
Payroll in Papua New Guinea rests on two deductions: salary or wages tax, assessed per fortnight, and superannuation. A new Income Tax Act has applied since 1 January 2026, and the minimum wage rose to K5.00 an hour the same day.
Our Partners Globally




Calculate Your Employee Costs in Papua New Guinea
Enter a gross annual salary to see the employer’s statutory cost in Papua New Guinea for 2026: 8.4% superannuation on base salary, compulsory for employers with 15 or more employees.
Employment Cost Calculator
*Indicative figures only and not definitive legal advice. Local regulations change frequently. Consult an expertPapua New Guinea
| British Pound | Papua New Guinea | |
|---|---|---|
| Base Salary (per month) | ||
| Employer Contributions | ||
| Total Cost (Annual) | ||
| Total Cost (Monthly) |
“Their expertise and understanding of the unique hiring, payment, and human resource practices in each country has been nothing short of outstanding. Our Client Success Manager, has done just that … ensured our success. Her availability and willingness to engage on a personal level has made all the difference.”
“Excellent service, especially from our account manager who has gone above and beyond to help us use the platform effectively. Our manager, significantly simplifies my workload. It is like having your own TopSource HR representative on your team.”
“TopSource has been our go-to resource for international hiring. They are responsive, thorough, respectful and knowledgeable. The Client Success team has provided us with the utmost customer service, and the more we use TopSource, the more, it gives us access to more resources and knowledge.”
Employer Costs in Papua New Guinea Explained
Papua New Guinea has no social security system, so the employer’s statutory cost is the 8.4% superannuation contribution, and only once you have 15 employees. Salary or wages tax and the employee’s 6% come out of pay. Here’s the breakdown.
Salary or wages tax is withheld by the employer and is a final tax for employees with no other income, so most never file a return. It is assessed per fortnight, whatever the pay period: residents pay 0% on the first K770, 30% up to K1,270, 35% up to K2,693, 40% up to K9,615 and 42% above, in line with annual bands of K20,000, K33,000, K70,000 and K250,000.
Non-residents pay 22% on the first K770 a fortnight and the same rates above it. Residents with dependants get a tax credit of up to K1,050 a year. The Income Tax Act 2025 took effect on 1 January 2026 and replaced the 1959 Act. It kept these rates and thresholds, but salary packaging benefits are now capped at 40% of the total package and need the Commissioner General’s prior approval.
Under the Superannuation (General Provisions) Act 2000, an employer with 15 or more employees contributes 8.4% of each employee’s base salary to an authorised superannuation fund and deducts 6% from the employee, once the employee has been continuously employed for three months. Base salary excludes overtime, bonuses and commission.
Membership is compulsory for PNG citizens and voluntary for foreign employees, and smaller employers can join voluntarily at the same rates. Contributions are due within 14 days of the end of each month. The Bank of Papua New Guinea enforces the rules, and failing to pay is an offence that carries a fine of up to K500,000.
The national minimum wage is K5.00 an hour from 1 January 2026 under Minimum Wages Board Determination No. 1 of 2025, up from K3.50, and rises to K5.25 in January 2027 and K5.50 in January 2028. On the 44-hour week the Employment Act uses to calculate overtime, that is K220 a week and K440 a fortnight.
The Employment Act 1978 treats as overtime any time over eight hours on a weekday, Saturday work after noon and all work on Sundays and public holidays. Overtime is paid at time and a half and Sunday work at double time, and work on a public holiday earns the normal day’s pay plus the hourly rate for the hours worked. No one may be required to work more than 12 hours a day, and employees get at least 24 consecutive hours of rest each week.
For a resident employee earning K3,000 a fortnight, about K78,000 a year, an employer with 15 or more staff adds K252 of superannuation: a fortnightly cost of K3,252, or 8.4% on top of salary. Below 15 employees the statutory cost is the salary itself, because there is no employer payroll tax.
The employee pays K770.85 of salary or wages tax and K180 of superannuation and takes home K2,049.15, before any dependant credit. Wages are paid at least every two weeks, or monthly by agreement.
Employees earn 14 consecutive days of paid recreation leave for each year of continuous service, and anyone leaving after at least six months is paid one day for each completed month. After six months of service, employees with a medical certificate get six days of paid sick leave a year, which can build up to 18 days.
Women who have worked 108 days in the past 12 months, or 90 days in the past six, are entitled to maternity leave for any hospital stay before the birth and six weeks after it, plus up to four more weeks if they are ill. It is unpaid unless they convert recreation or sick leave credits, and nursing mothers get two paid half-hour breaks a day. Without a notice clause in the contract, notice is one day in the first four weeks, one week up to a year, two weeks up to five years and four weeks after that, the same for both sides.
Papua New Guinea payroll tax and superannuation, 2026
| Item | Employer | Employee | Applies to |
|---|---|---|---|
| Superannuation | 8.4% | 6% | Base salary, employers with 15 or more employees, PNG citizens |
| Salary or wages tax, residents | — | 0% to 42% | Tax-free up to K770 a fortnight, K20,000 a year |
| Salary or wages tax, non-residents | — | 22% to 42% | 22% from the first kina |
| Dependant tax credit | — | Up to K1,050 a year | Residents with up to three dependants |
| Social security tax | None | None | No state social security scheme |
| Salary or wages tax deadline | 7th of the next month | — | Withholding return and payment |
| Superannuation deadline | 14 days after month end | — | Paid to an authorised superannuation fund |
Salary or wages tax per fortnight from 1 January 2026
| Fortnightly income | Residents | Non-residents |
|---|---|---|
| Up to K770 | 0% | 22% |
| K770 to K1,270 | 30% | 30% |
| K1,270 to K2,693 | 35% | 35% |
| K2,693 to K9,615 | 40% | 40% |
| Above K9,615 | 42% | 42% |
Gross to net and employer cost in Papua New Guinea, per fortnight
| Fortnightly gross | Employee deductions | Net pay | Employer superannuation | Total fortnightly cost |
|---|---|---|---|---|
| K1,500 | K320.50 | K1,179.50 | K126.00 | K1,626.00 |
| K3,000 | K950.85 | K2,049.15 | K252.00 | K3,252.00 |
| K6,000 | K2,330.85 | K3,669.15 | K504.00 | K6,504.00 |
The gross-to-net table assumes a resident employee with no dependants, paid fortnightly, whose employer has 15 or more employees. Employee deductions are salary or wages tax and the 6% superannuation contribution. These are TopSource calculations from the verified rates.
Rates, thresholds and amounts shown were verified on 9 October 2026 against the Income Tax Act 2025 (Schedule 1 and its withholding provisions), the Superannuation (General Provisions) Act 2000 and the Bank of Papua New Guinea’s notice on superannuation contributions, the Employment Act 1978 and Minimum Wages Board Determination No. 1 of 2025. This page is general information, not tax or legal advice.
How our Papua New Guinea payroll service works
Why Choose TopSource for Global Payroll in Papua New Guinea
TopSource for payroll, Employer of Record or any other of our services represents a simpler, more reliable and transparent option.
We don’t hide fees or sneak price increases. We run Papua New Guinea payroll in-house and file under your own Internal Revenue Commission and superannuation fund registrations rather than a bureau’s, so the same team that pays your salary or wages tax answers your calls. You get a named account manager, one consolidated monthly invoice covering salaries, contributions and fees, and one live Portico view of Papua New Guinea beside every other country we run for you. Portico syncs with your time-tracking, leave and HR systems via API – set up by our onboarding team, not left to yours. GDPR, SOC 2 and ISO 27001 certified.
Other services
Accelerating your growth in Papua New Guinea and beyond
TopSource goes far beyond payroll, acting as your end-to-end partner in global workforce management. From Employer of Record (EOR) services and seamless entity setup to localized accountancy and fractional HR support, we cover every aspect of international employment.
Meet our experts for Papua New Guinea
Whether you’re entering the market or scaling operations, our specialists provide the insight and guidance you need to succeed in one of the world’s most dynamic and regulated employment landscapes. With TopSource, you’re backed by real experts, every step of the way.
Beyond a payroll serviceA globalization accelerator
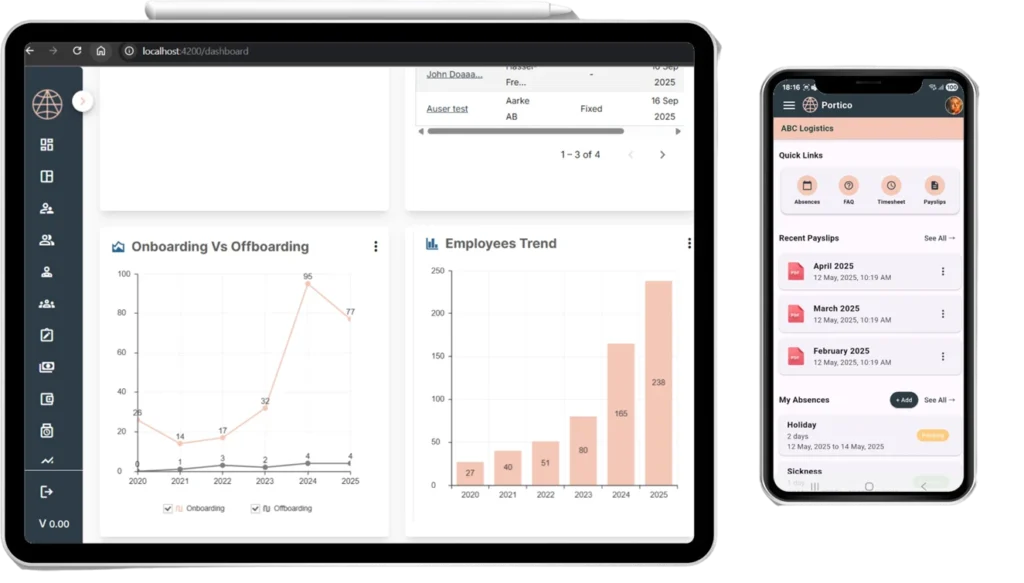
Payroll platform
Global payroll simplified
Your intuitive hub for paying global teams. Simple, powerful, and designed to scale with you — no complexity, just clarity.
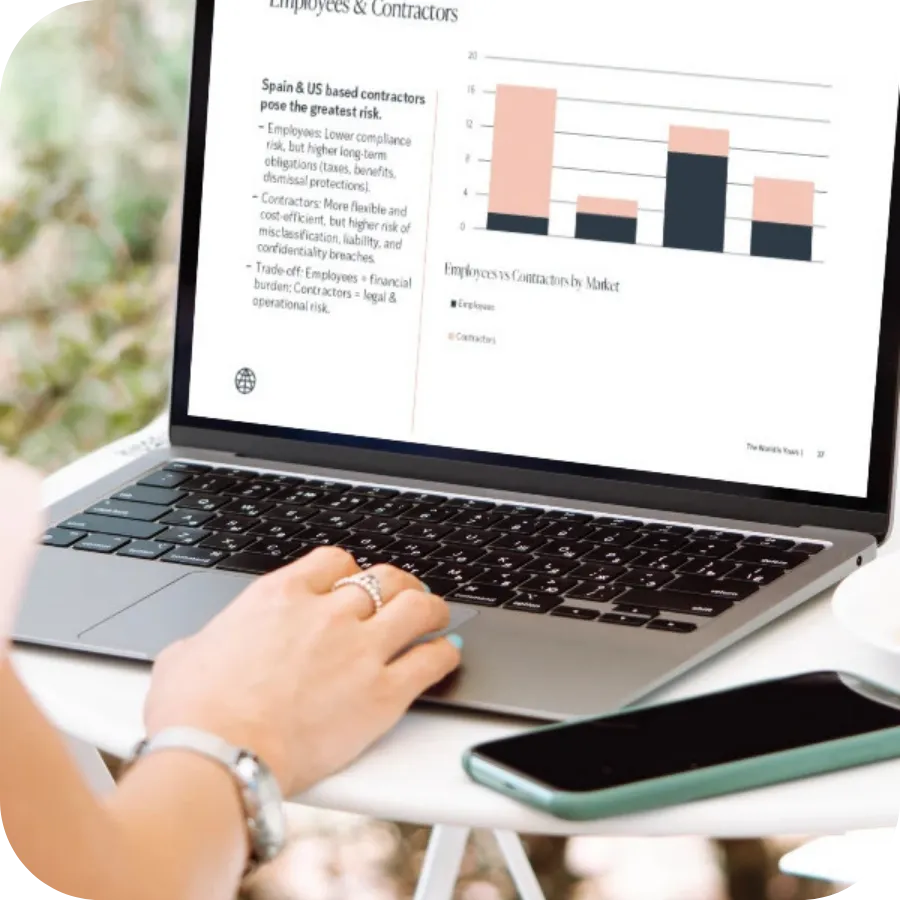
Audit
Eliminate barriers to growth
Avoid compliance issues across your global workforce and uncover opportunities to improve profitability. On a quarterly basis we’ll help you audit your global talent strategy to ensure it aligns with your business goals.
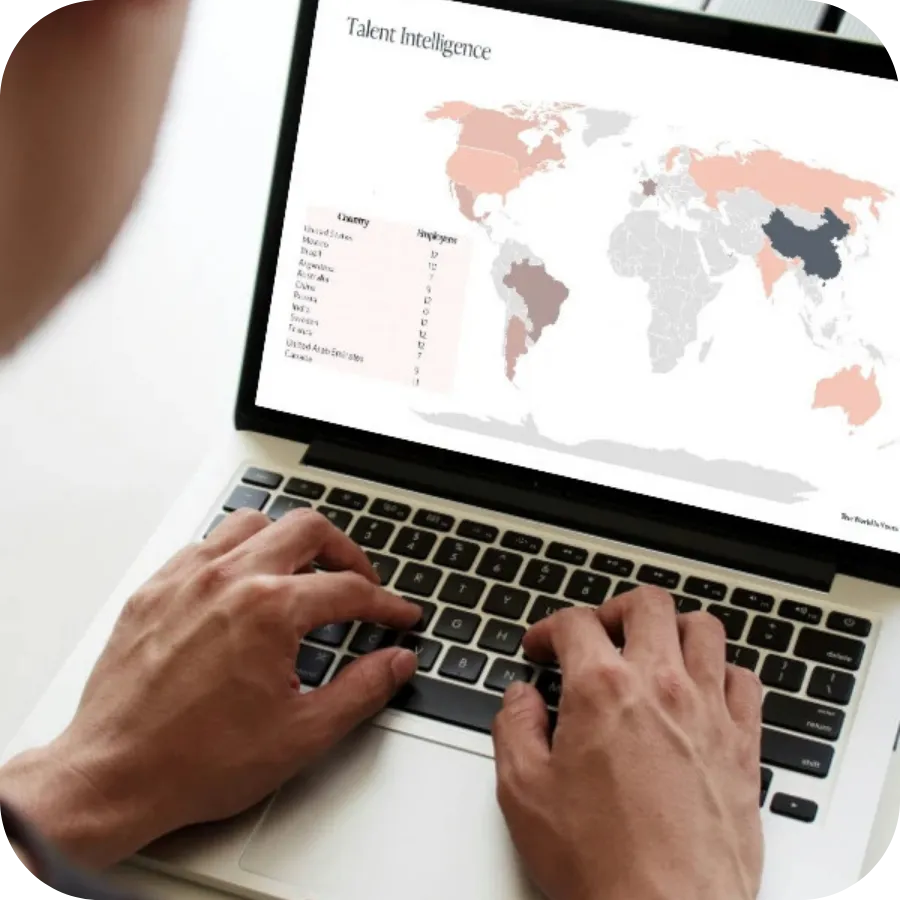
Intelligence
Build a data-driven talent strategy
Grow confidently and profitably with access to the latest TopSource insights & data on hiring markets, salary benchmarking & benefits.
Advisory
Expert guidance that turns complexity into clarity.
Whether you’re managing a global acquisition or entering a new market, you get clear guidance to navigate complex decisions, avoid delays, and accelerate your global expansion.
Papua New Guinea payroll FAQs
Only superannuation: employers with 15 or more employees pay 8.4% of base salary for PNG citizens with three months of service and deduct 6% from the employee. There is no social security tax or payroll levy on the employer.
It is assessed per fortnight. Residents pay 0% on the first K770, then 30%, 35%, 40% and 42%, in line with annual bands of K20,000, K33,000, K70,000 and K250,000. Non-residents pay 22% on the first K770. The employer withholds it as a final tax.
It replaced the Income Tax Act 1959 on 1 January 2026. The rates and thresholds for employment income stayed the same, but salary packaging is capped at 40% of the package with prior approval, and some benefits, such as company cars, are valued differently.
K5.00 an hour since 1 January 2026, up from K3.50, under Minimum Wages Board Determination No. 1 of 2025. It is set to rise to K5.25 in January 2027 and K5.50 in January 2028.
By the 7th of the month after the month in which the salary was paid, with the withholding return. Employers also file an annual withholding tax statement within three months of the end of the year, by 31 March.
For employers with 15 or more employees, yes: they pay 8.4% of base salary and deduct 6% for each PNG citizen employee with three months of service, within 14 days of month end. Smaller employers and foreign employees can contribute voluntarily.
An employee on K3,000 a fortnight costs K3,252 with superannuation, 8.4% on top of pay, and takes home K2,049.15 after tax and super. Tell us the role and salary and we’ll send the full cost within one business day.
At least 14 consecutive days of paid recreation leave for each year of continuous service, plus six days of paid sick leave a year after six months of service, with a medical certificate.
Without a notice clause, the Employment Act 1978 requires one day in the first four weeks, one week up to a year, two weeks up to five years and four weeks after that, the same for employer and employee.
Employers register with the Internal Revenue Commission and an authorised superannuation fund, which in practice requires a local company or branch. TopSource can run payroll for your Papua New Guinea entity or employ your team through our Employer of Record service.
Looking at other markets too?
We help organizations employ and pay teams in 164 countries.