Payroll Services in New Zealand
Fully managed New Zealand payroll in New Zealand dollars – KiwiSaver at the 3.5% rate that took effect on 1 April 2026, ESCT tiered from the right year rather than defaulted to 10.5%, your ACC classification unit checked because it decides most of your statutory cost, and Employment Information filed within two working days of every payday including the out-of-cycle ones, with a named specialist a phone call away.

TopSource rated 5/5 by our customers
What New Zealand payroll actually involves
New Zealand has one of the lightest employer statutory burdens anywhere and one of the hardest leave regimes. There is no employer social security at all – no payroll tax, no employer social insurance, no state pension contribution – so employer cost is KiwiSaver at 3.5% plus the ACC levies, about 3.7% for an office-based business. But the ACC Work levy runs from 2 cents to $5.32 per $100 of earnings depending on the classification unit, so what the business does matters more than what it pays. Filing is per payday, within two working days, with no monthly consolidation. The employer’s superannuation contribution is itself taxed, on tiers set from the prior year. And the Holidays Act 2003 runs four different pay calculations for different kinds of leave, which is why private-sector employers paid over $237 million in holiday pay remediation between 2015 and 2020. The replacement Act passed in August 2026 and cannot be used until August 2028. Cheap to employ, and easy to get wrong.
Our Partners Globally




Calculate Your Employee Costs in New Zealand
Enter a gross annual salary to see the full employer cost of a New Zealand employee – KiwiSaver at the compulsory 3.5%, plus the ACC levies for an office classification unit: the Work levy at 13 cents per $100 for corporate head office and management consulting, and the Working Safer levy at 8 cents, both capped at $156,641 of liable earnings. ESCT is not added, because it is deducted from the KiwiSaver contribution rather than charged on top. A different classification unit changes the Work levy – anywhere from 2 cents to $5.32 per $100.
Employment Cost Calculator
*Indicative figures only and not definitive legal advice. Local regulations change frequently. Consult an expertNew Zealand
| British Pound | New Zealand | |
|---|---|---|
| Base Salary (per month) | ||
| Employer Contributions | ||
| Total Cost (Annual) | ||
| Total Cost (Monthly) |
“Their expertise and understanding of the unique hiring, payment, and human resource practices in each country has been nothing short of outstanding. Our Client Success Manager, has done just that … ensured our success. Her availability and willingness to engage on a personal level has made all the difference.”
“Excellent service, especially from our account manager who has gone above and beyond to help us use the platform effectively. Our manager, significantly simplifies my workload. It is like having your own TopSource HR representative on your team.”
“TopSource has been our go-to resource for international hiring. They are responsive, thorough, respectful and knowledgeable. The Client Success team has provided us with the utmost customer service, and the more we use TopSource, the more, it gives us access to more resources and knowledge.”
Employer Costs in New Zealand Explained
Employer statutory cost in New Zealand is about 3.7% of salary for an office-based employer – roughly a quarter of the United Kingdom’s. The reason is simple: there is no employer social security of any kind. What there is, is KiwiSaver at 3.5% of gross from 1 April 2026, rising to 4% in 2028, plus two ACC levies – the Work levy, averaging 69 cents per $100 of liable earnings but ranging from 2 cents to $5.32 depending on the classification unit, with most office units between 2 and 13 cents, and the flat Working Safer levy at 8 cents. Both ACC levies cap at $156,641 of earnings per employee, so the effective rate drifts down to 3.61% at $300,000. Two things are commonly got wrong. ESCT does not add to the cost: it is deducted from the employer’s contribution before it reaches the scheme, so employer cost is 3.5% of gross and not 3.5% times 1.33. And the ACC earners’ levy of 1.75% is employee-paid, inside the PAYE tables, not an employer charge. Here’s the breakdown.
The compulsory employer contribution is 3.5% of gross salary or wages from 1 April 2026, up from 3%, with a further increase to 4% legislated for 1 April 2028. Both changes came out of Budget 2025. The employee minimum moved on the same date and anyone sitting on 3% was moved to 3.5% automatically; employees already electing 4%, 6%, 8% or 10% were unaffected, and the default for a new employee who does not choose is now 3.5%. Two related changes landed with it. Compulsory employer contributions extended to 16- and 17-year-olds who are already members – though note they are not auto-enrolled, so the obligation is to contribute for an existing member rather than to enrol anyone. And the government contribution was halved to 25 cents per dollar with a maximum of $260.72 a year and no entitlement above $180,000 of taxable income; that one is paid by Inland Revenue direct to the scheme and appears on no payroll line, but employees ask about it constantly.
A new mechanism arrived with the rate rise and it is the one most likely to be mishandled. Because 3% no longer exists as a standing election, members who want it must apply for a temporary rate reduction, which runs for three months to a year, can be taken back to back, and can be revoked early. It cannot be held at the same time as a savings suspension. The critical payroll point is that while a reduction is in force the employer may match down to 3% as well – the contribution floor drops with the employee. And it expires: Inland Revenue notifies the member about thirty days beforehand and the rate reverts to 3.5%, so an employer that does not diary the expiry silently keeps contributing 3% against a 3.5% obligation. On a job change the employee has to show the new employer the acceptance letter for the reduced rate to continue at all.
ESCT is where international cost models go wrong, so it is worth being exact. New Zealand taxes the employer’s superannuation contribution on five tiers – 10.5% to $18,720, 17.5% to $64,200, 30% to $93,720, 33% to $216,000 and 39% above that – and the tax is deducted from the contribution rather than charged on top of it. On a $100,000 salary the 3.5% contribution is $3,500; an employee in the 33% band means $1,155 of ESCT, the scheme receives $2,345, and the employer’s cost remains $3,500. Employer cost is 3.5% of gross, full stop. It is not 3.5% multiplied by 1.33, and budgeting it that way overstates New Zealand employer cost by about a third.
The tier itself is set from the prior year, and this is the classic configuration error. For an existing employee the rate comes from last year’s salary plus last year’s employer contributions, is fixed on 1 April, and is held for the whole year whatever happens to their pay – so an employee who doubles their salary in May stays on the old lower rate until the following April, which is correct and looks like a bug. The mirror-image failure is worse: a new employee must be rated on an estimate of the current year, but a system asked what this employee earned with us last year answers nil and defaults them to 10.5%. A senior hire who should be on 39% gets 10.5% for their entire first year. And a third-order trap specific to 2026/27 – the tier threshold is salary plus the gross employer contribution, so when the contribution rose from 3% to 3.5% some employees crossed an ESCT band for that reason alone. Any employer that recalculated ESCT from salary alone on 1 April 2026 has part of its workforce on the wrong rate.
Employer statutory cost in New Zealand is about 3.7% of salary for an office-based employer. There is no employer social security of any kind – no payroll tax, no employer social insurance, no state pension contribution. The whole of it is KiwiSaver at 3.5% plus two ACC levies: the Work levy, which depends entirely on what the business does, and the Working Safer levy at a flat 8 cents per $100 of liable earnings, which funds WorkSafe New Zealand rather than ACC. Both are capped at liable earnings of $156,641 per employee, so the effective rate drifts down above that – 3.71% at $100,000 and 3.61% at $300,000.
The Work levy is the variable, and the average is close to meaningless. ACC sets it by classification unit, an industry code reflecting injury risk, and for 2026/27 the average is 69 cents per $100 while the actual range runs from 2 cents for computer systems design to $5.32 for professional rugby and thoroughbred jockeys. Office classifications sit at the very bottom – accounting 3 cents, legal services 5 cents, management consulting and corporate head offices 13 cents – while plumbing is $1.43, logging $2.32, roofing $2.39 and shearing $2.98. At $80,000 of salary that is the difference between $104 and $1,912 a year on the Work levy alone between a head office and a roofing business, which takes total employer cost from 3.71% to 5.97%. Getting the classification unit right is therefore worth more than any other single decision in a New Zealand cost model, and misallocation – usually inherited from whoever first registered the business, and often coding a mixed business to its highest-risk activity – is both common and expensive.
Two things changed in 2026/27 that most guides have not caught. The No-Claims Discount was discontinued on 1 April 2026, inside the current year, on the stated basis that it did not deliver the expected health and safety improvements. It applied to self-employed people and small businesses, and a small employer that budgeted for it this year will find it gone. What remains is Experience Rating, which needs a Work levy of $10,000 or more for three consecutive years to qualify – so smaller employers now have no claims-history mechanism at all. Experience Rating offers up to a 50% discount or up to a 100% loading, weighted by recency, and participants pay a 7.2% programme rate that is separate from any discount. Separately, the levy rates for 2025/26, 2026/27 and 2027/28 were all set together in December 2024, which means the 2027/28 figures are already fixed and can be modelled with confidence – unusually good forward visibility.
One number on the employee side causes more confusion than anything else. The ACC earners’ levy is set by ACC at $1.52 per $100 of liable earnings excluding GST, and collected by Inland Revenue at 1.75% including GST. Those are the same levy – $1.52 × 1.15 is 1.748 – and mixing the two documents produces a 15% error. It is employee-paid, embedded in the PAYE tables rather than shown as a separate payslip line, capped at $156,641, and worth at most $2,741.22 a year. It is also why the secondary tax codes look wrong to anyone comparing them with the headline income tax rates: the SB code deducts 12.25%, not 10.5%, because the rate quoted is income tax plus the earners’ levy.
PAYE income tax for 2026/27 runs at 10.5% to $15,600, 17.5% to $53,500, 30% to $78,100, 33% to $180,000 and 39% above that. It is a clean full year – the thresholds moved on 31 July 2024 and produced a composite eight-bracket schedule for that year only, which has caused lingering confusion, but they have applied in full since 1 April 2025 and there is no transitional complication in the live year. The Independent Earner Tax Credit delivers up to $520 a year through the ME tax code for employees earning $24,000 to $70,000, abating at 13 cents in the dollar above $66,000.
The deduction stack runs in a specific order and each element has its own rules. PAYE – income tax plus the 1.75% earners’ levy, applied by tax code – comes first. Then student loan at 12% of earnings above $24,128 a year on a main job, and here there is an asymmetry that generates complaints: on a secondary job 12% applies to every dollar with no threshold at all, because the threshold is deemed used by the main job. Then the KiwiSaver employee contribution. Then child support on notice from Inland Revenue, subject to protected net earnings so that deductions cannot take more than 40% of net pay. Payroll giving, where offered, reduces PAYE directly by 33.33% of the donation in the same pay period rather than being claimed at year end. Tax codes are declared on the IR330 for employees and the IR330C for contractors, and where no IR330 is provided the no-declaration rate deducts 45% – 46.75% with the levy.
Bonuses and lump sums do not use a flat rate. The method looks back four weeks at regular pay excluding any extra pay, annualises it by thirteen if paid more often than monthly or twelve if monthly, adds the secondary code’s low threshold where one applies, adds the lump sum, and reads the marginal rate off the resulting total. One carve-out is regularly missed: the earners’ levy applies to most lump sums but not to redundancy payments, retiring allowances or employee share scheme benefits. A performance bonus carries the levy; redundancy does not.
Fringe benefit tax is a separate return on its own cycle, and it is conflated with payroll constantly. Changes took effect on 1 April 2026, and they created a cost that very few employers have modelled. Where an employer elects to put a benefit through PAYE rather than through FBT – the option is attractive for gift cards and unclassified benefits – the amount enters the employee’s gross earnings. Gross earnings drive average weekly earnings, average weekly earnings drive the greater-of test, and the greater-of test drives holiday pay. So an FBT election made for administrative simplicity quietly raises the cost of every subsequent annual holiday. The same applies to electing to treat an employer superannuation contribution as salary rather than deducting ESCT: it is rarely cheaper, and it inflates Holidays Act gross earnings.
The Employment Relations Amendment Act 2026 came into force on 21 February 2026 and made four changes that matter to an employer. Employees on remuneration of $200,000 or more a year can no longer bring an unjustified dismissal personal grievance – note $200,000, not the $180,000 in the Bill as introduced. It applies to new employment agreements, with a twelve-month transition for existing ones, and it will be indexed annually from 1 July 2027. Two consequences are worth planning around: an existing high earner keeps dismissal protection until their agreement is replaced, and because a promotion above $200,000 usually means a new agreement, promotion can strip protection unless the parties expressly contract back in, which the Act permits in writing.
Second, where an employee’s own conduct contributed to the situation, the Employment Relations Authority and the Employment Court are now required to reduce or remove certain remedies rather than merely having a discretion to do so. Reinstatement and compensation for hurt and humiliation may be withheld entirely, although reimbursement of lost wages can still be ordered. That is a meaningful shift in employer exposure on a contested dismissal. Third, the thirty-day rule under which a new employee in a role covered by a collective agreement had to be employed on the collective’s terms for their first month was removed.
Fourth, and most useful commercially, there is now a gateway test for contractor status. A worker is a specified contractor – and cannot claim to be an employee – only where all five conditions are met: a written agreement stating they are an independent contractor; no restriction on working for others; either control over their own working times or a right to subcontract; a right to decline additional work without the arrangement ending; and a reasonable opportunity to take independent legal advice before signing. It is a safe harbour rather than a new test, so failing the gateway does not create employment – the common law control and economic-reality analysis applies instead. It is not retrospective.
Two other things are settled and worth stating plainly. The 90-day trial period has been available to all employers, regardless of size, since 23 December 2023, but it must be agreed in writing and in good faith before the employee starts work – signing on day one voids it, and that is litigated regularly. And New Zealand has no statutory redundancy compensation at all: no formula, no minimum weeks per year of service, no state fund. Redundancy pay exists only where the employment agreement provides for it, and many New Zealand agreements are lawfully silent. What the law does require is a fair process – a genuine business reason, genuine consultation, consideration of redeployment – and the exposure for getting that wrong is an unjustified dismissal grievance, not a statutory payment. A personal grievance must be raised with the employer within 90 days, extended to twelve months for sexual harassment, and then filed with the Authority within three years.
Annual holidays are four weeks after twelve months of continuous employment – weeks, not days or hours, which matters because a five-day worker gets twenty days and a three-day worker gets twelve. Annual holiday pay is then the greater of two separately computed figures: ordinary weekly pay, being what the employee receives for an ordinary working week including regular allowances and consistent overtime, and average weekly earnings, being gross earnings over the preceding twelve months divided by 52. Both must be calculated on every occasion, and the higher one paid. For casual and genuinely intermittent employees an 8% pay-as-you-go alternative exists, but it applies only where the employment genuinely has no fixed pattern, and drift into using it for regular part-timers creates double liability.
Public holidays, sick leave, bereavement leave, family violence leave and alternative holidays use a different pair of calculations again. Relevant daily pay is what the employee would have earned had they worked that day. Average daily pay is gross earnings over the past 52 weeks divided by the number of days worked. Average daily pay is not a free choice – relevant daily pay is the default, and average daily pay may be used only where relevant daily pay cannot practicably be determined or where the employee’s daily pay varies within the pay period. Systems configured to use average daily pay as standard because it automates more easily are non-compliant, and because it is usually lower for anyone with recent overtime, that configuration underpays.
So four different pay calculations coexist – ordinary weekly pay, average weekly earnings, relevant daily pay and average daily pay – each with its own inclusion rules and its own trigger conditions, applying to different leave types. That, rather than any single rule, is why New Zealand has had systemic holiday pay failure: between November 2015 and June 2020 private-sector employers paid over $237 million in holiday pay remediation to 227,300 employees. The other structural causes are that entitlement is expressed in weeks while payment happens in days or hours with no single statutory conversion; that gross earnings is broader than base pay and includes commission, regular overtime, allowances and benefits elected into PAYE; and that legacy systems typically encode one method and compound the error silently for years.
The rest of the leave framework is more straightforward. Ten days paid sick leave after six months, arriving as a block rather than accruing, carrying over to a maximum of twenty days. Bereavement leave of three days for an immediate family member and one day otherwise. Up to ten days paid family violence leave, which does not carry over and is not paid out on termination. Paid parental leave of 26 weeks, funded entirely by government and paid by Inland Revenue at up to $811.05 a week from 1 July 2026 – the employer pays nothing, and the rate changes mid-tax-year each July, so the 2026/27 year spans two maximums. There are twelve public holidays including a regional anniversary day, and Matariki is a moveable feast: always a Friday, set by a thirty-year schedule aligned to the Māori lunar calendar, and shifting by up to three weeks year to year. It falls on Friday 10 July 2026 and Friday 25 June 2027. A hard-coded date, or an assumption that it sits in late June, will be wrong. Mondayisation then means the same calendar date can be a public holiday for one employee and an ordinary working day for a colleague, depending on whether they would normally work that day.
New Zealand employer contribution rates, 2026/27 (all figures in New Zealand dollars)
| Contribution | Employer | Employee | Applies to |
|---|---|---|---|
| KiwiSaver – compulsory employer contribution | 3.5% | 3.5% minimum | Of gross salary or wages, from 1 April 2026. Rises to 4% on 1 April 2028 |
| KiwiSaver – employee rates available | — | 3.5% / 4% / 6% / 8% / 10% | Default 3.5%. 3% only via a temporary rate reduction |
| ESCT | 10.5% – 39% | — | Deducted FROM the employer contribution, not added to it. Five tiers |
| ACC Work levy | $0.69 per $100 average | — | By classification unit: $0.02 to $5.32. Most office units $0.02 to $0.13. Capped at $156,641 of earnings |
| ACC Working Safer levy | $0.08 per $100 | — | Flat, all employers. Funds WorkSafe New Zealand. Same earnings cap |
| ACC earners’ levy | — | 1.75% | Employee-paid, inside the PAYE tables. Capped at $156,641, max $2,741.22 |
| PAYE income tax | — | 10.5% / 17.5% / 30% / 33% / 39% | Thresholds $15,600 / $53,500 / $78,100 / $180,000 |
| Student loan | — | 12% | Above $24,128 a year on a main job. No threshold at all on a secondary job |
| Employer social security | Nil | — | There is none. No payroll tax, no employer social insurance, no state pension levy |
| Paid parental leave | Nil | — | 26 weeks, government-funded, paid by Inland Revenue at up to $811.05 a week |
| Statutory redundancy | Nil | — | New Zealand has none. Contractual only |
| Total employer statutory cost | ≈ 3.7% for an office classification unit | — | KiwiSaver 3.5% + ACC. See the cost tables below |
What changed in 2026, and what changes next
| Item | Position before | Position now | Note |
|---|---|---|---|
| KiwiSaver employer contribution | 3% | 3.5% | Rises again to 4% on 1 April 2028 |
| KiwiSaver employee minimum | 3% | 3.5% | Moved automatically for anyone on 3% |
| Employee rates available | 3 / 4 / 6 / 8 / 10% | 3.5 / 4 / 6 / 8 / 10% | 3% survives only as a temporary rate reduction |
| Compulsory contributions for 16–17 year olds | None | 3.5% | Existing members only – they are still not auto-enrolled |
| Government contribution | 50c per $1, max $521.43 | 25c per $1, max $260.72 | From 1 July 2025. No entitlement above $180,000 of income |
| ACC No-Claims Discount | Available | ABOLISHED | Discontinued 1 April 2026. Experience Rating needs $10,000 of Work levy for 3 years |
| Unjustified dismissal – high earners | All employees protected | Excluded at $200,000+ | In force 21 February 2026. New agreements; 12-month transition. Indexed from 1 July 2027 |
| Contractor status | Common law test only | Five-condition gateway test | In force 21 February 2026, not retrospective. A safe harbour, not a new test |
| Fringe benefit tax | Pre-2026 rules | Changed 1 April 2026 | A PAYE election puts the benefit into gross earnings – and so into holiday pay |
| Holidays Act | Holidays Act 2003 | Holidays Act 2003 | Employment Leave Act 2026 assented 6 Aug 2026, commences 6 Aug 2028. Early adoption PROHIBITED |
Employer statutory cost by salary, 2026/27 (office classification unit)
| Salary | KiwiSaver 3.5% | ACC levies | Total | Effective rate | Note |
|---|---|---|---|---|---|
| $60,000 | $2,100.00 | $126.00 | $2,226.00 | 3.71% | Below the ACC cap – cost is proportional |
| $80,000 | $2,800.00 | $168.00 | $2,968.00 | 3.71% | Roughly the median full-time salary |
| $100,000 | $3,500.00 | $210.00 | $3,710.00 | 3.71% | ESCT at 33% comes out of the $3,500, not on top |
| $156,641 | $5,482.44 | $328.94 | $5,811.38 | 3.71% | Exactly at the ACC liable earnings cap |
| $200,000 | $7,000.00 | $328.94 | $7,328.94 | 3.66% | ACC stops rising here; KiwiSaver does not |
| $300,000 | $10,500.00 | $328.94 | $10,828.94 | 3.61% | ESCT at 39%, still carved out of the contribution |
The classification unit, which decides most of the answer
| Component | At $60,000 | At $80,000 | At $100,000 | Note |
|---|---|---|---|---|
| KiwiSaver employer contribution | $2,100 | $2,800 | $3,500 | 3.5% of gross. Rises to 4% on 1 April 2028 |
| ACC Work levy – head office CU 78560 | $78 | $104 | $130 | $0.13 per $100. Legal $0.05, accounting $0.03, IT systems $0.02 |
| ACC Work levy – roofing CU 42230 | $1,434 | $1,912 | $2,390 | $2.39 per $100 – the same employee, 18× the levy |
| ACC Working Safer levy | $48 | $64 | $80 | $0.08 per $100, flat for every employer |
| Employer social security | $0 | $0 | $0 | There is none in New Zealand |
| Statutory redundancy provision | $0 | $0 | $0 | No statutory entitlement. Contractual only |
| Total, head office classification unit | ≈ $2,226 | ≈ $2,968 | ≈ $3,710 | 3.71% at every level below the $156,641 cap |
| Total, roofing classification unit | ≈ $3,582 | ≈ $4,776 | ≈ $5,970 | 5.97% – the classification unit is the whole variable |
ESCT is deducted from the employer’s KiwiSaver contribution rather than charged on top of it, so it does not increase employer cost – the scheme receives the contribution net of ESCT while the employer pays the gross 3.5%. The ESCT tier is set from the employee’s prior-year salary plus the prior year’s gross employer contributions, fixed on 1 April and held for the whole year; a new employee must instead be rated on an estimate of the current year, which is where most systems default wrongly to 10.5%. Both ACC levies are calculated on liable earnings capped at $156,641 per employee. The cost tables assume classification unit 78560, corporate head office management services, at $0.13 per $100 plus the $0.08 Working Safer levy; twelve equal monthly payments with no bonus; and a KiwiSaver member contributing at or above the minimum. They exclude ESCT, the employee-paid earners’ levy and any Experience Rating discount or loading. Classification unit rates are ACC’s 2026/27 rates as confirmed by the Government in December 2024. These are TopSource calculations, not published figures.
Rates, thresholds and levies shown are for the 2026/27 tax year, which runs from 1 April 2026 to 31 March 2027, and were verified on 11 September 2026. All figures are in New Zealand dollars. PAYE thresholds, KiwiSaver rates, the minimum wage and the ACC levy year all change on 1 April; the paid parental leave maximum changes on 1 July, so the 2026/27 year spans two of them. ACC levy rates for 2025/26, 2026/27 and 2027/28 were set together in December 2024. The Holidays Act 2003 governs all leave calculations for this year and next – the Employment Leave Act 2026 does not commence until 6 August 2028 and cannot be adopted early. This page is general information, not tax or legal advice.
How our New Zealand payroll service works
Why TopSource for New Zealand Payroll
TopSource for payroll, Employer of Record or any other of our services represents a simpler, more reliable and transparent option.
We don’t hide fees or sneak price increases. We run New Zealand payroll in-house and file under your own Inland Revenue employer registration rather than a bureau’s, so the same team that files your Employment Information answers your calls. You get a named account manager, one consolidated monthly invoice covering salaries, KiwiSaver, PAYE and fees, and one live Portico view of New Zealand beside every other country we run for you. Portico syncs with your time-tracking, leave and HR systems via API – set up by our onboarding team, not left to yours. GDPR, SOC 2 and ISO 27001 certified.
Other services
Accelerating your growth in New Zealand and beyond
TopSource goes far beyond payroll, acting as your end-to-end partner in global workforce management. From Employer of Record (EOR) services and seamless entity setup to localized accountancy and fractional HR support, we cover every aspect of international employment.
Meet our experts for New Zealand
Whether you’re entering the market or scaling operations, our specialists provide the insight and guidance you need to succeed in one of the world’s most dynamic and regulated employment landscapes. With TopSource, you’re backed by real experts, every step of the way.
Beyond a payroll serviceA globalization accelerator
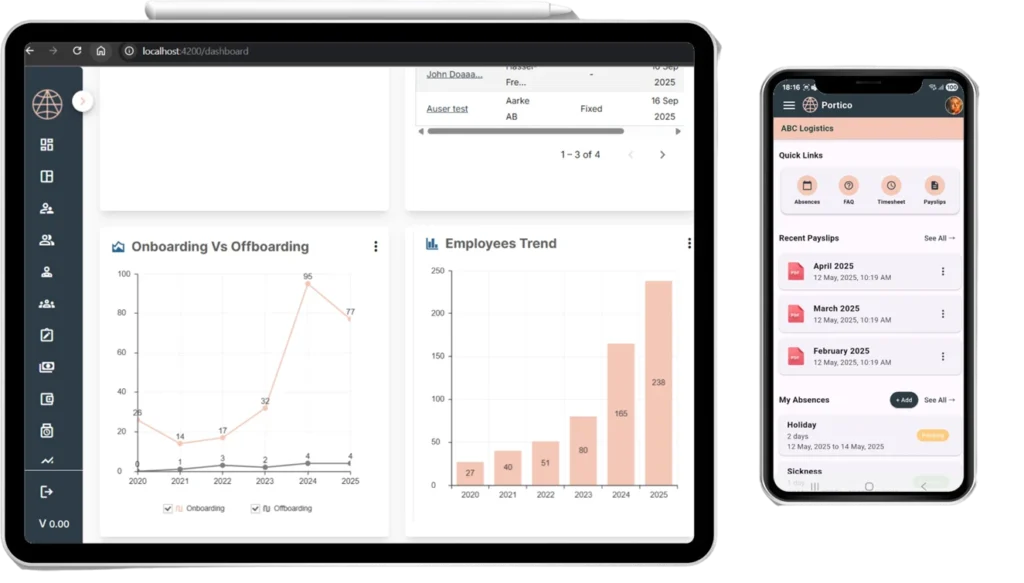
Payroll platform
Global payroll simplified
Your intuitive hub for paying global teams. Simple, powerful, and designed to scale with you — no complexity, just clarity.
Audit
Eliminate barriers to growth
Avoid compliance issues across your global workforce and uncover opportunities to improve profitability. On a quarterly basis we’ll help you audit your global talent strategy to ensure it aligns with your business goals.
Intelligence
Build a data-driven talent strategy
Grow confidently and profitably with access to the latest TopSource insights & data on hiring markets, salary benchmarking & benefits.
Advisory
Expert guidance that turns complexity into clarity.
Whether you’re managing a global acquisition or entering a new market, you get clear guidance to navigate complex decisions, avoid delays, and accelerate your global expansion.
New Zealand payroll FAQs
The compulsory employer contribution is 3.5% of gross salary or wages from 1 April 2026, up from 3%, and it rises again to 4% on 1 April 2028. It is payable for KiwiSaver members aged 16 to 64 with active deductions – the age floor dropped from 18 to 16 on 1 April 2026. The employer’s cost is 3.5% of gross: Employer Superannuation Contribution Tax is deducted from that contribution rather than charged on top of it, so the scheme receives less than 3.5% but the employer pays exactly 3.5%. Where an employee holds a temporary rate reduction the employer may match down to 3%.
From 1 April 2026 employees may elect 3.5%, 4%, 6%, 8% or 10% of gross salary or wages, and the default for someone who does not choose is 3.5%. The 3% rate was removed from the standing menu – anyone who was on it was moved to 3.5% automatically. An employee who wants 3% must apply to Inland Revenue for a temporary rate reduction, which lasts three months to a year, can be taken back to back, and cannot be held at the same time as a savings suspension. It expires automatically and the rate reverts to 3.5%, so the expiry date has to be tracked in payroll.
ESCT is Employer Superannuation Contribution Tax, and it does not increase employer cost – it is deducted from the employer’s contribution before the money reaches the scheme. Rates run on five tiers: 10.5% up to $18,720, 17.5% to $64,200, 30% to $93,720, 33% to $216,000 and 39% above that, based on the employee’s prior-year salary plus the prior year’s gross employer contributions. On a $100,000 salary the 3.5% contribution is $3,500, ESCT at 33% is $1,155, the scheme receives $2,345, and the employer’s cost is still $3,500. Budgeting 3.5% plus ESCT overstates New Zealand employer cost by about a third.
Employment Information must reach Inland Revenue within two working days of each payday for electronic filers, or within ten working days for the paper filers who are still permitted to use it. There is no monthly consolidation – every payday triggers its own filing, and an out-of-cycle payment such as a final termination pay is a separate payday with its own two-day clock. PAYE and deductions are paid by the 20th of the following month, or twice monthly for employers whose annual PAYE and ESCT reach $500,000. Late filing costs $250 per month, charged once regardless of how many filings are late in that month.
Annual holiday pay is the greater of ordinary weekly pay and average weekly earnings, calculated separately on every occasion leave is taken. Ordinary weekly pay is what the employee receives for an ordinary working week, including regular allowances and consistent overtime; average weekly earnings is gross earnings over the preceding twelve months divided by 52. Public holidays, sick leave and bereavement leave use a different pair – relevant daily pay by default, with average daily pay available only where relevant daily pay cannot practicably be determined or where daily pay varies within the pay period. Four coexisting calculations are the main reason private-sector employers paid over $237 million in holiday pay remediation between November 2015 and June 2020.
No. New Zealand has no statutory redundancy compensation – no formula, no minimum weeks per year of service and no state fund. Redundancy pay is payable only where the employment agreement provides for it, and many New Zealand agreements are lawfully silent on it. What the law does require is a fair process: a genuine business reason, genuine consultation and consideration of redeployment. The exposure for getting that wrong is an unjustified dismissal personal grievance rather than a statutory payment. A redundancy payment is taxed as an extra pay under the lump-sum method and is exempt from the ACC earners’ levy.
Not since 21 February 2026, if they earn $200,000 or more a year. The Employment Relations Amendment Act 2026 removed the right to bring an unjustified dismissal personal grievance for employees on remuneration at or above that threshold, which will be indexed annually from 1 July 2027. It applies to new employment agreements, with a twelve-month transition for existing ones, and the parties may agree in writing to retain dismissal protection. Other grievance grounds – discrimination, harassment, unjustified disadvantage – remain available regardless of income. Note that a promotion above the threshold usually means a new agreement, so it can remove protection unless the parties contract back in.
The adult minimum wage is $23.95 an hour from 1 April 2026, up from $23.50, set by the Minimum Wage Order 2026 and announced on 12 December 2025. The starting-out and training rates are both $19.16, set at 80% of the adult rate. There is no separate youth minimum wage; the starting-out rate applies to specified categories of 16- to 19-year-olds and the training rate to employees in recognised industry training of at least 60 credits a year. The rate is reviewed annually, with the decision announced each December for a 1 April start.
Matariki falls on Friday 10 July 2026 and Friday 25 June 2027. It is a moveable public holiday – always a Friday, but the date is set by a thirty-year schedule aligned to the Māori lunar calendar and the rise of the Matariki star cluster, and it shifts by up to three weeks from year to year. Introduced in 2022, it was New Zealand’s first new national public holiday since 1974. A payroll or leave system with a hard-coded date, or one that assumes it sits in late June, will be wrong. New Zealand has twelve public holidays in total, being eleven national days plus a regional anniversary day that varies by location.
The government does. Paid parental leave is 26 weeks, funded entirely by the state and paid by Inland Revenue direct to the employee at up to $811.05 gross a week from 1 July 2026 – the employer pays nothing. The maximum rate is reviewed each 1 July, so it changes mid-tax-year; $788.66 applied from 1 April to 30 June 2026. The employer’s obligations are to hold the job open and to manage keeping-in-touch hours, which let an employee do limited paid work during leave without ending the payment. The minimum rate for self-employed people is $239.50 a week, being ten hours at the adult minimum wage.
Looking at other markets too?
We help organizations with employ and pay teams in over 180 countries.